
Buying
Construction Loans Townsville
If you are weighing a build against an established house, the finance is not neutral between them. Loans for new dwellings sit outside the debt-to-income cap lenders have been rationing since February 2026, so building can clear a hurdle that an established purchase at the same price will not.
We arrange construction loans Townsville wide, for new builds, house-and-land packages and knockdown rebuilds, including the land where it has not settled yet. The contract is where these applications actually fail, so it gets read before anything is lodged.
Get Your Build Finance Sorted in Townsville
Your land, your builder, and the contract or tender if you have one yet.
What We Handle On a Build
We check your building contract will clear the conditions a lender sets, structure the loan around the payment schedule in that contract, then chase each progress claim through the build so your builder is not left waiting on funds. Where the block has not settled, the land purchase is arranged first and the construction facility sits behind it.
There is no cost to you for any of it. The lender pays us a commission on settlement, so having a tender looked at before you sign is free, and before you sign is when it is worth doing.
How Your Build Gets Funded
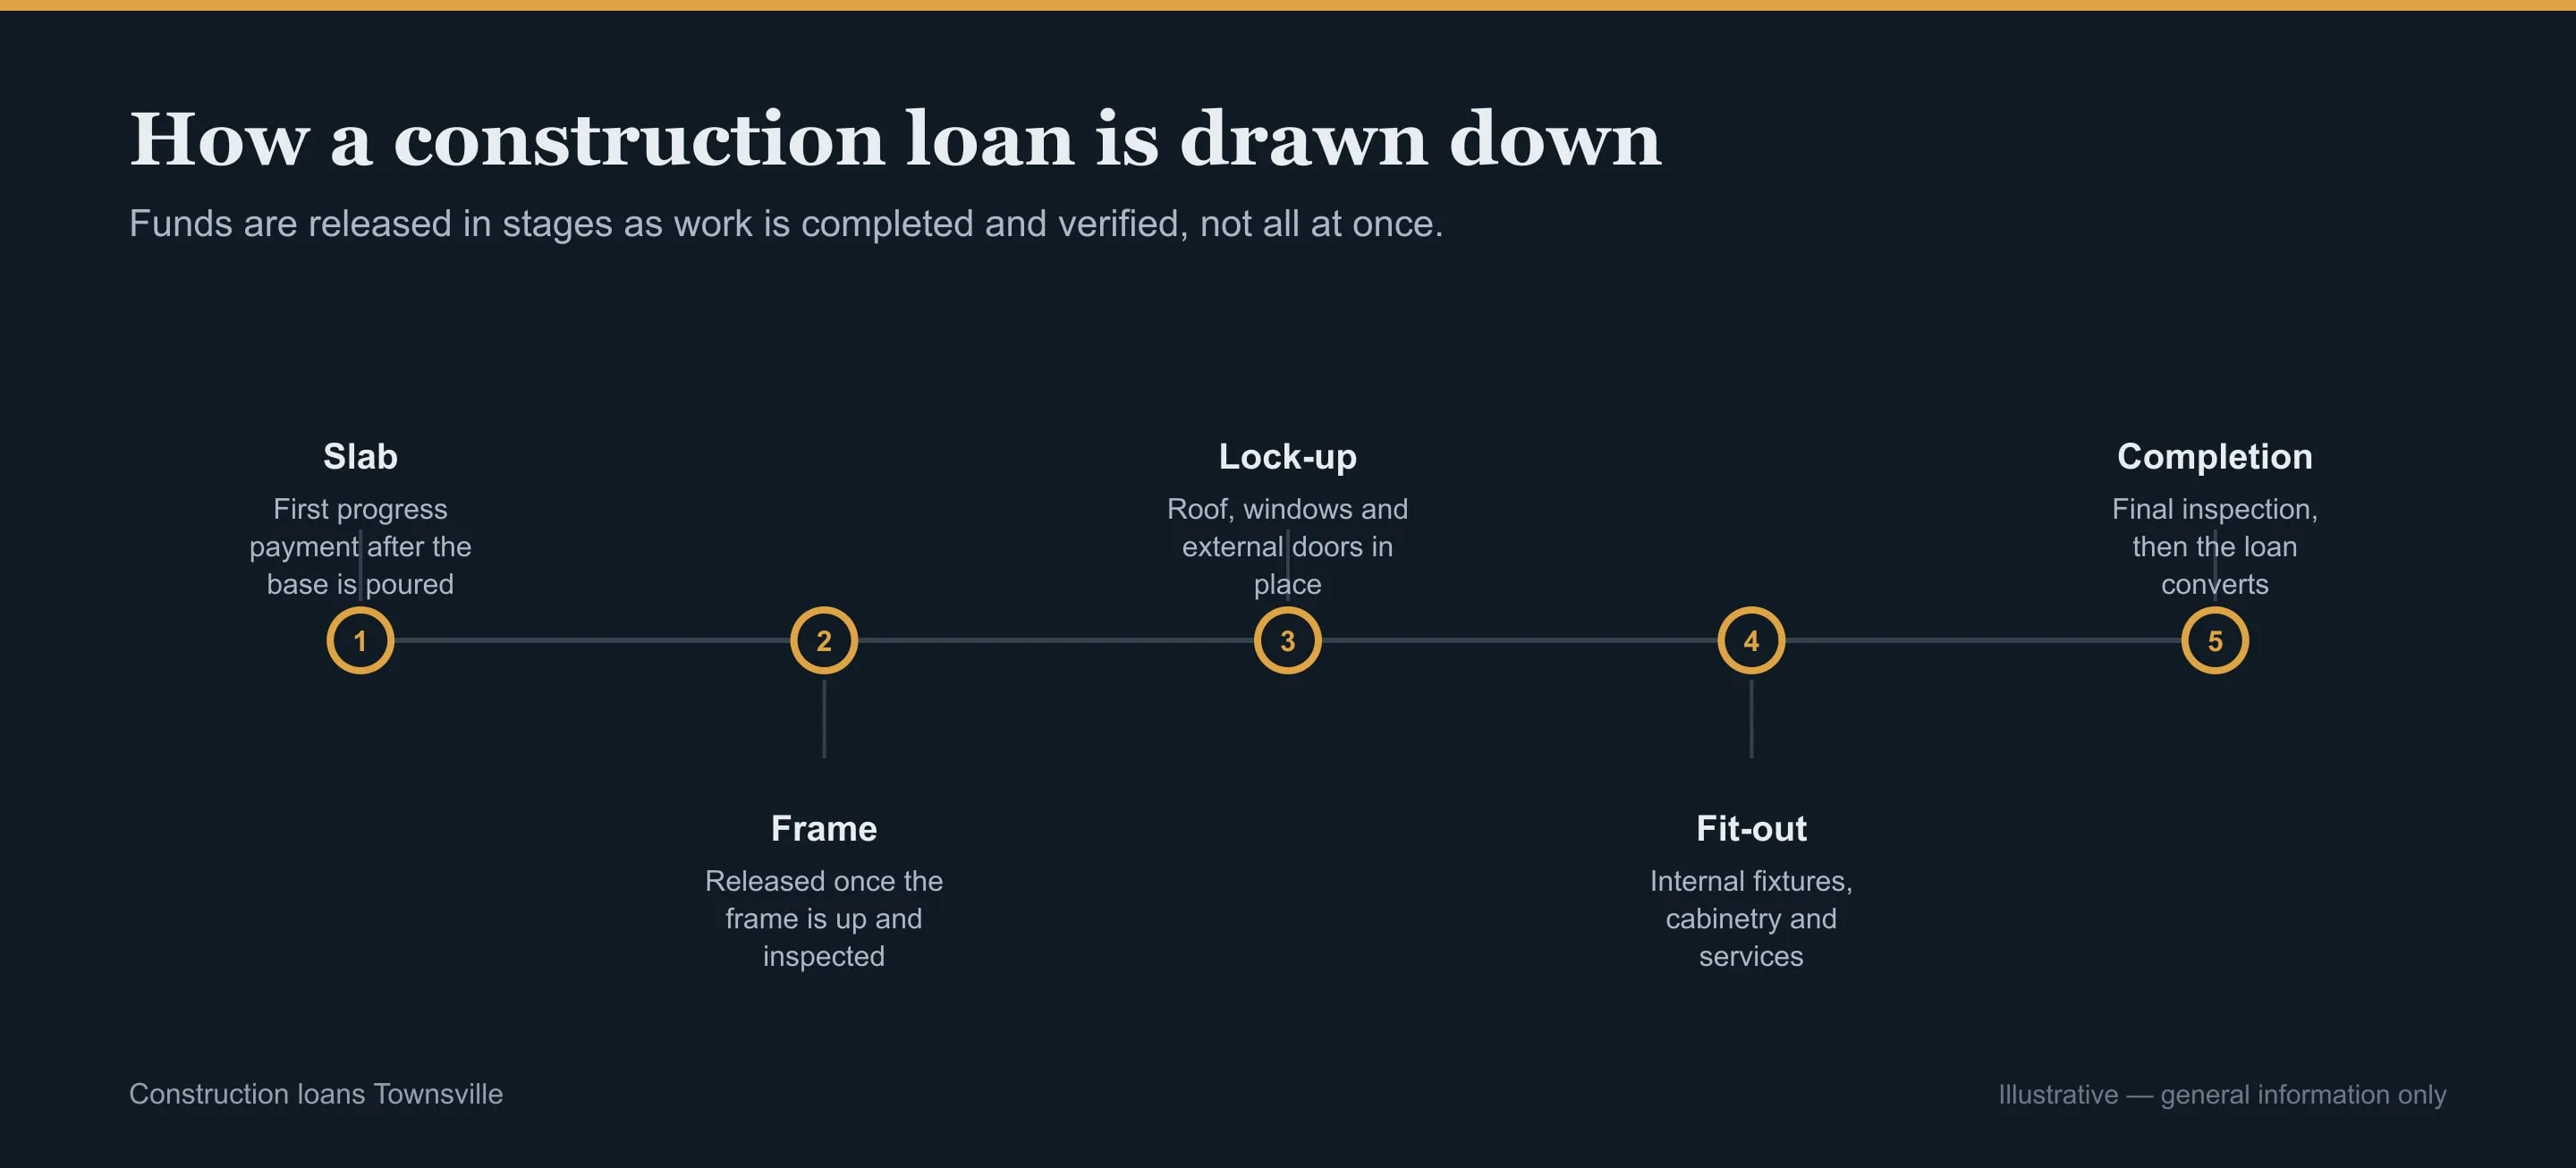
A construction loan does not hand you the money at once. It pays your builder in stages as the work is completed, and each stage has to be verified before the funds move.
-
We fund the land first if you need it
Where the block has not settled, the land purchase comes first and the construction facility sits behind it. Have the contract of sale and your plans or tender ready.
Before construction starts
-
We get the contract and the builder approved
The lender assesses the fixed-price contract, the builder’s licence and insurance, and the plans. This is where files most often stall, so we check it before lodging rather than after.
Days, not weeks, if the contract is clean
-
The lender releases funds stage by stage
Slab, frame, lock-up, fit-out and completion. Your builder invoices, the lender inspects or values, and the money is released. We chase each drawdown so your builder is not waiting.
Across the build
-
The loan converts on completion
Once the final inspection and occupancy certificate are done, the facility converts to a standard home loan. We review the structure at that point rather than letting it roll over unexamined.
At handover
Before You Sign Anything
What do you need from me before I sign a building contract?
The tender or draft contract, the plans, your builder’s details, and the land contract if the block has not settled. We would rather look at the contract before you sign it than work around a term that makes it hard to finance.
How long does construction finance take to arrange?
The loan approval runs on similar timeframes to a standard home loan, but the contract and builder verification adds a step. A clean fixed-price contract with a licensed builder moves quickly. A cost-plus or owner-builder arrangement takes considerably longer and narrows the lender list.
Do you charge for helping with a construction loan?
No. The lender pays a commission when the loan settles. There is no fee to you for the assessment, the contract review or managing the drawdowns.
What You Pay While The House Is Being Built
You are only charged interest on what has actually been drawn, not on the full approved amount. At slab stage that is a small fraction of the loan; by lock-up it is most of it. Your payments rise through the build and only become full principal and interest repayments once the house is finished.
The number that catches people is the overlap. If you are renting or still paying a mortgage elsewhere while the build runs, you are carrying both, and the construction cost climbs every month. We model that overlap from the start and factor your rent or existing repayments into the assessment, because a build that services comfortably on completion can be tight in month eight.
Why The Building Contract Decides Your Approval
Lenders fund construction against a fixed-price contract with a licensed builder, not against an estimate. In Queensland your builder must hold a QBCC licence for the work and, for residential building over the statutory threshold, the contract must be covered by the Queensland Home Warranty Scheme. If the licence, the insurance or the contract terms do not line up, the lender will not release funds regardless of how good your finances are.
Cost-plus contracts, owner-builder arrangements and contracts with large provisional sums are all harder to finance, and some lenders will not touch them at all. If that is what you are holding, tell us early, because it changes the lender shortlist entirely rather than just adding a condition.
We check the contract, the licence and the insurance before anything is lodged. It is the single most common reason a construction application is delayed, and it is entirely preventable.
Building To Cyclone Standards
Townsville sits in cyclone Region C under the Australian wind loading standards, which means your build has to meet wind classifications that a southern build does not. Tie-downs, roof fixings, glazing and cladding all have to be specified accordingly, and that is priced into your contract rather than added later.
Two things follow from that for your finance. Your contract price will be higher than an equivalent build in a non-cyclonic region, so a budget carried over from a southern comparison will be short. And your insurance from completion will reflect the same exposure, because North Queensland premiums run well above the national average, which is a holding cost worth getting quoted before you commit, not after handover.
A properly engineered new build is generally cheaper to insure than an older house of similar value, because it is built to current standards. That is one of the few places where building rather than buying established works in your favour on cost, and it is worth pricing rather than assuming.
The Exemption That Makes Building Easier To Finance
From 1 February 2026 APRA limits lending at six times income or above to twenty per cent of a lender’s new loans, and lenders near that quarterly limit tighten up on high-DTI applications. Loans for new dwellings are exempt from that cap.
That is a genuinely useful lever. If your debt-to-income ratio is close to the line and an established purchase is running into resistance, building can put you outside the constraint that is causing the problem. It is not a reason to build on its own, but where you are weighing a new build against an established house at a similar price, it can be the thing that decides which one a lender will actually approve.
We check where your ratio sits before you commit to a property type, so the decision is made with the constraint visible rather than discovered at assessment.
Build costs are not listed here. Your contract price depends on the builder, the block and the wind classification of the specific site. Get it from a tender, not from a benchmark.
Building And Buying Land Around Townsville
Land release in the growth corridors south and north of the city has kept new stock coming, and a house-and-land package is often the more straightforward finance because the builder and the contract are known quantities to the lender.
The thing to check before you buy the block is the valuation on completion. The lender values the finished house, and in newer estates a valuation can land below the combined land-plus-build cost if comparable sales in the estate have not caught up. That gap becomes deposit you have to find at handover, not at the start. We flag it when the numbers look tight, and structure the finance so you are not discovering it in the final month.
Contracts, Builders And Drawdowns
What happens if my builder goes under mid-build?
This is what the Queensland Home Warranty Scheme is for on eligible residential contracts, and it is a large part of why lenders insist on a licensed builder and proper insurance. We check that cover is in place before funds are released rather than assuming it.
Can I be an owner-builder and still get finance?
Some lenders will consider it, most will not, and those that do usually require a larger deposit and stricter stage verification. Tell us up front if that is your plan, because it changes which lenders are worth approaching from the outset.
Do I pay full repayments while the house is being built?
No. You pay interest only on the funds drawn so far, so payments start small and increase with each stage. Full principal and interest repayments begin once the build is complete and the loan converts.
About us
Who Chases Your Drawdowns
The person who answers checks the contract before it is lodged and then chases each progress claim through the build. That happens at slab, frame, lock-up, fit-out and completion, so it is worth knowing who is doing it.
A builder waiting on a drawdown moves crews to the job that is paying, and around Townsville the trades are booked far enough ahead that getting them back is the hard part.
-
Call
Monday to Friday, 9am to 5pm
-
Use the form
Better if you are on shift or on site and cannot talk
-
Email
info@mortgagebrokertownsville.net.au
Useful if you already have documents to hand over
-
Where we are
Townsville, QLD 4810
The city, the northern beaches and the districts inland
Get Your Build Finance Sorted in Townsville
If you have a tender but have not signed anything yet, that is the useful moment to have the contract looked at.
Call (07) 4463 8031 Use The Form
Prefer to start from the beginning? Our Mortgage Broker Townsville page covers what we do and how we are paid.