
Investing
Investment Loans Townsville
The yield that draws investors north is calculated before insurance. North Queensland premiums run well above the national average because of cyclone exposure, and on a flood-overlay address the cover can move from expensive to unobtainable, which is the single most common reason a local purchase misses the return its spreadsheet promised.
We arrange investment loans Townsville wide, on net numbers rather than headline ones. What the rent counts for after a lender has shaded it, what the holding costs actually are, and a structure that leaves the next purchase possible instead of closing the door on it.
Get Your Townsville Investment Structured
What you already own, what you earn, and the property or price bracket you are weighing up.
How We Work an Investment File
We model the property on rent a lender will actually count, work out where your existing loans are limiting you, and choose a structure before choosing a lender. That covers a first investment purchase, adding to a portfolio that has stopped servicing, and Defence Housing Australia leaseback properties, which several lenders treat differently from a standard purchase.
It costs you nothing to have the numbers run. We are paid a commission by the lender when a loan settles, so the modelling and the comparison are free, including where they show the purchase does not work.
From Numbers To Settlement
Investment finance is structured before it is applied for. Getting the order right is most of the work.
-
We map what you hold now
Existing loans, equity positions, rental income and how each is currently structured. This is where most of the borrowing capacity you did not know you had turns up.
Day one
-
We model the property properly
Rent, insurance, rates, management and vacancy against the loan. Bring the rental appraisal and the rates notice if you have them, or we will estimate from comparable stock.
-
We choose the structure and the lender
Interest-only or principal and interest, whether to cross-secure or keep loans standalone, and which lenders have appetite for investor lending this quarter.
Before anything is lodged
-
We lodge and settle it
Application, valuation, conditions and settlement, coordinated with your conveyancer and, if it is tenanted, the managing agent.
Through to settlement
Before You Get In Touch
What do you need from me to work out what I can borrow?
Your income, statements for any existing loans, the rental income you currently receive, and the price bracket you are looking at. If you already have a property in mind, the rental appraisal and rates notice help us model it accurately.
Does using a broker cost me anything for an investment loan?
No. The lender pays a commission on settlement. There is no fee to you for a standard residential investment loan, and no charge if you decide not to proceed.
How Lenders Read Your Rental Income
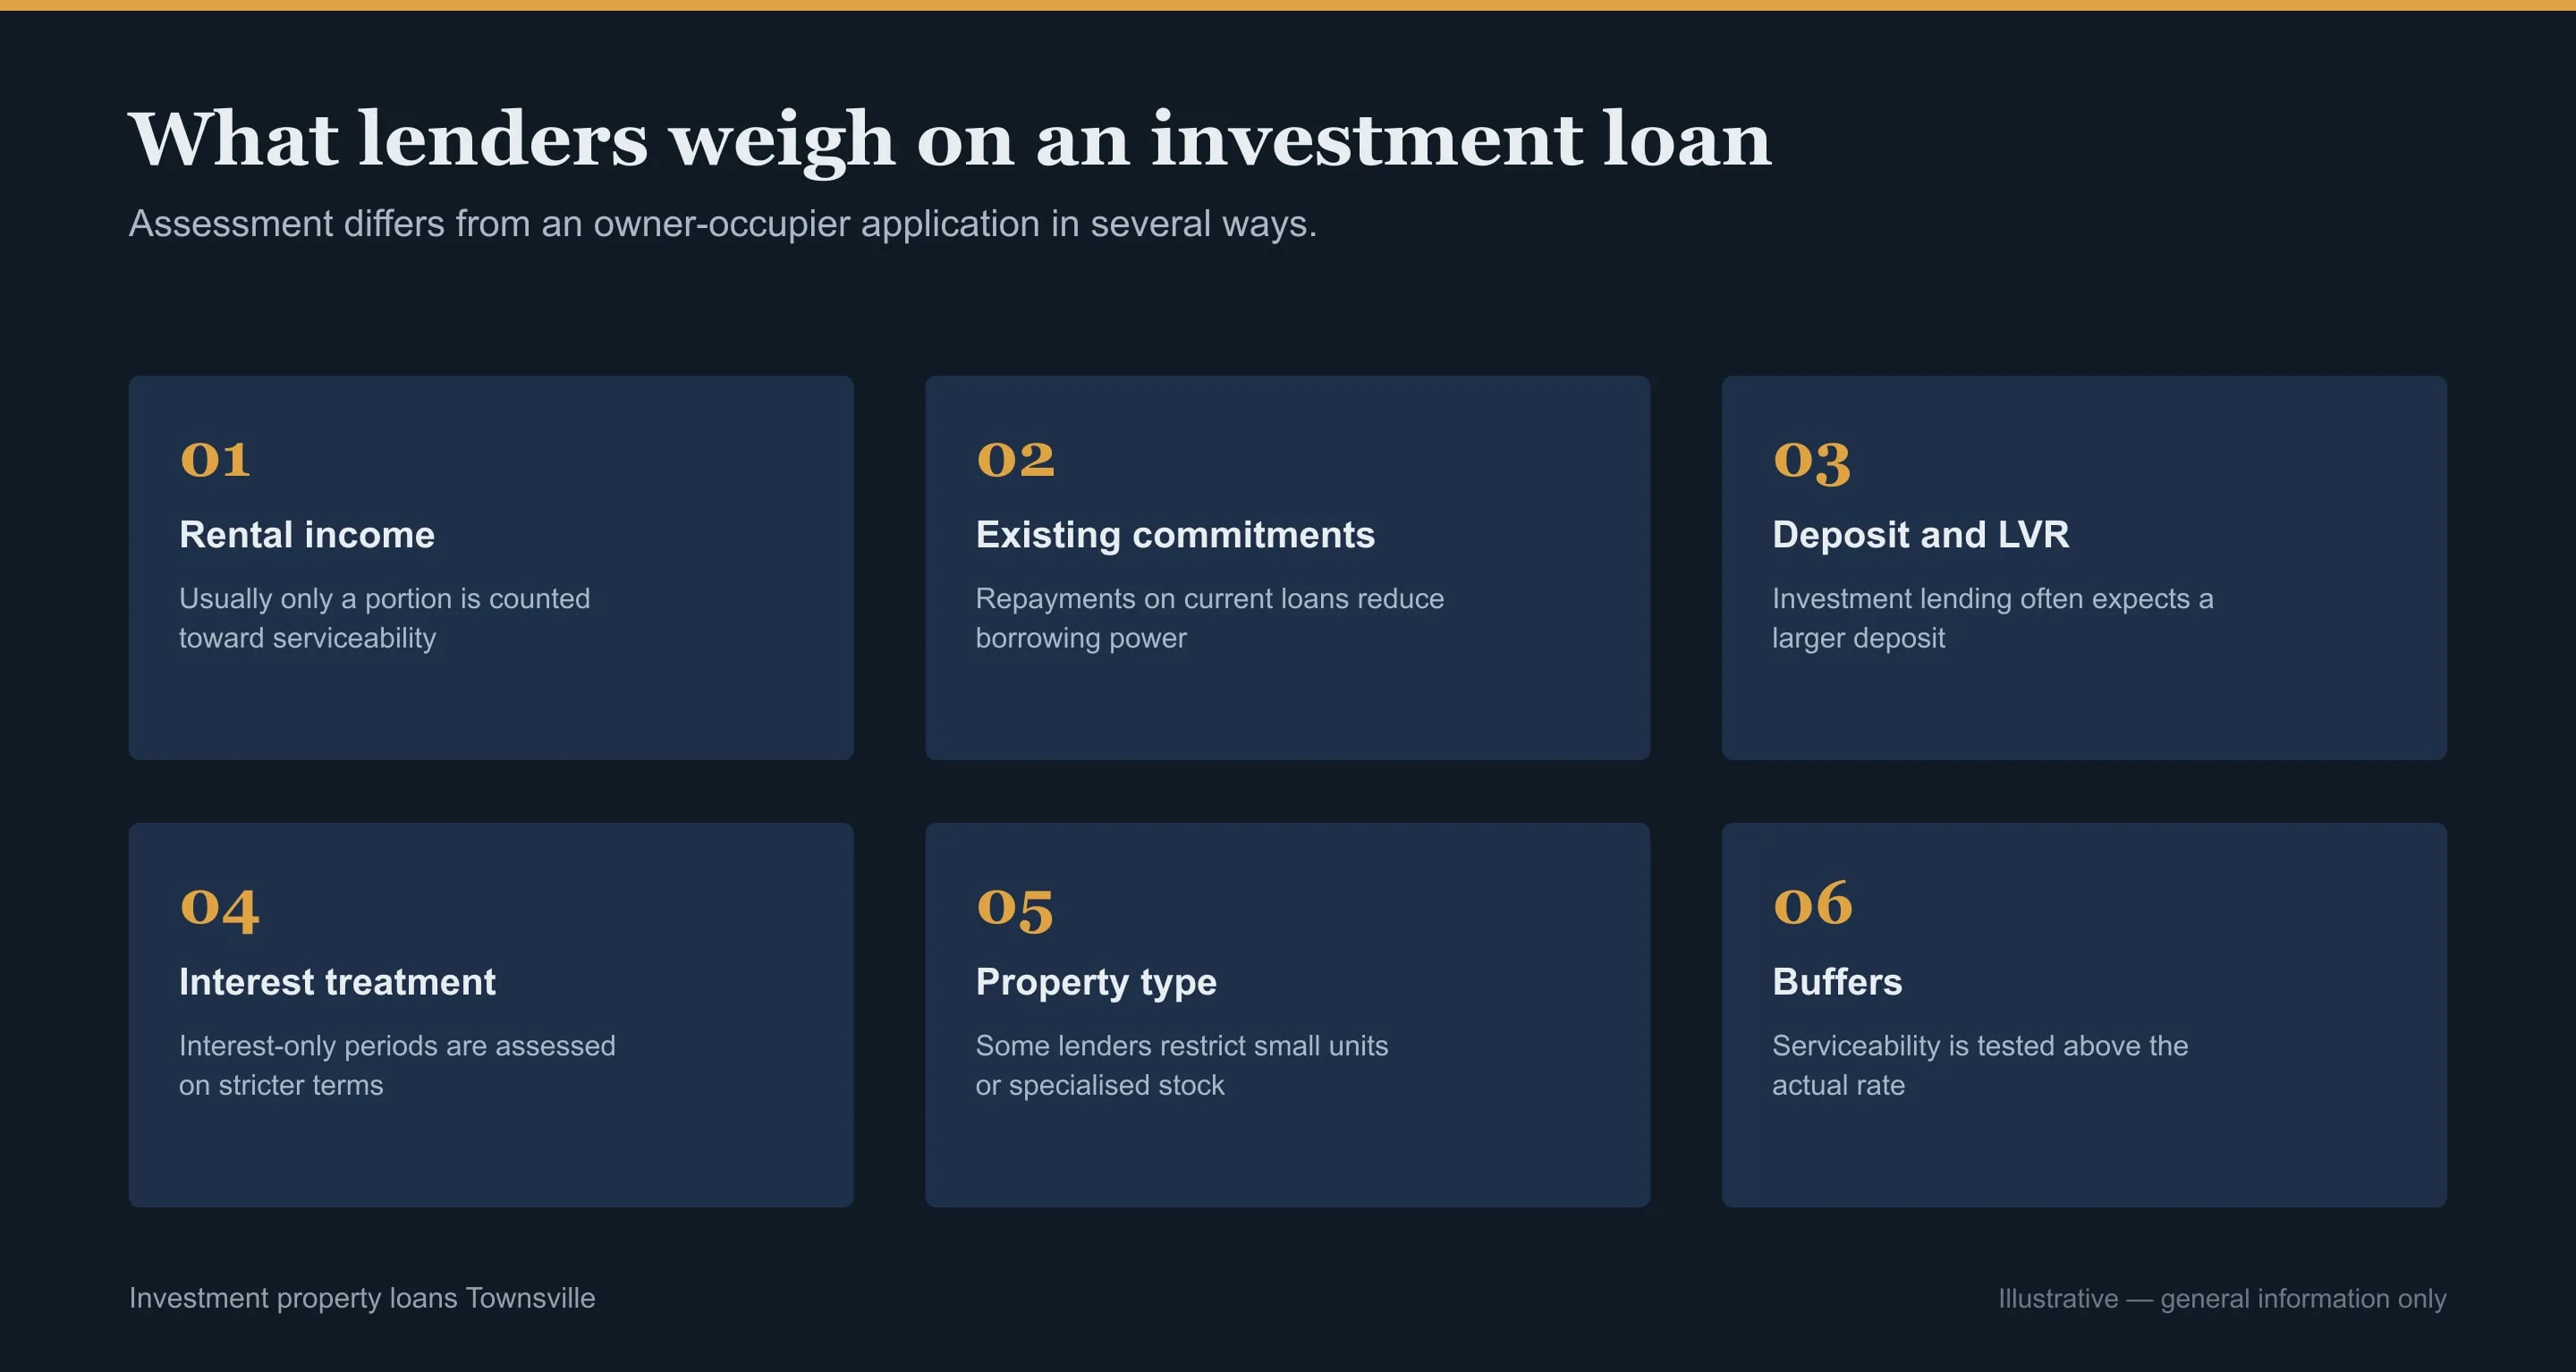
No lender counts rent in full. Most apply a discount to allow for vacancy, management fees and maintenance, and the size of that discount varies enough between lenders to change whether an application works at all. The same property with the same rent can serve comfortably at one bank and fall short at another.
Rent is also assessed against a loan tested three percentage points above the actual rate, so a property that looks cash-flow neutral on paper still has to survive a buffer the market is not currently applying. We model it that way from the start so the figure we give you is the one the assessor will reach.
Where an existing portfolio is the constraint, the fix is often in the structure rather than the income. Loans crossed against each other, redraw sitting where an offset should be, or an interest-only period quietly expiring all reduce what you can do next. We look at that before we look at the new purchase.
The Investor Cap And Why Timing Matters
From 1 February 2026 APRA restricts lending at or above six times debt-to-income to twenty per cent of a lender’s new loans, and critically, investor lending is measured separately from owner-occupier lending, quarter by quarter.
For an investor with existing debt that is the constraint that bites, because your total borrowings across every property count toward the ratio. It also means the answer moves. A lender comfortably inside its investor limit in one quarter can be rationing high-DTI approvals in the next. We check where lenders currently sit before choosing where to lodge, rather than applying somewhere on reputation and waiting three weeks for a decline.
What Holding Costs Actually Come To Here
Yields in Townsville have been strong relative to the southern capitals, which is what draws investors north. The number to plan against is the one after costs, and in North Queensland insurance is the line that decides the return.
Cyclone exposure means home insurance in northern Australia has long run well above the national average, and premiums here have been reported at multiples of what the same cover costs in a southern city. If the property sits in a flood overlay, insurance can move from expensive to genuinely difficult, and some insurers will not write it at all. We ask you to get an actual quote on the specific address before you commit rather than budgeting from a rule of thumb, because it is the single most common reason a Townsville investment underperforms its spreadsheet.
Body corporate levies on units carry the same problem for the same reason. A unit that looks cheap against a house often is not once the strata insurance component is included.
Insurance is deliberately absent from this table. It varies too much by address, build and flood overlay for any figure to be meaningful. Get a quote on the specific property.
Buying a Defence Housing Australia Property
DHA leaseback properties are common around Townsville and they suit some investors well. DHA leases the property from you for a fixed term, pays rent whether or not it is tenanted, and manages it, which removes vacancy risk and most management effort in exchange for a management fee deducted from the rent.
The trade-offs are real. The management fee is higher than a standard agency, you have limited say over the property during the lease, and your resale market at the end is narrower because the buyer pool for a leased DHA property is smaller than for an unencumbered house. Not every lender treats DHA rental income the same way either, and a few restrict the loan-to-value ratio on them.
We will tell you which lenders accept them, how the DHA rent is assessed, and whether the guaranteed income is worth what it costs you. It is a legitimate structure. It is just not automatically the better one, and it deserves the same comparison as any other purchase.
Where Investors Are Buying Around Townsville
The rental market has been tight, with vacancy reported below one per cent through 2025 and 2026 and rents rising faster than the national average. That is the fundamental driving investor interest here, alongside the defence population, the port, and mining services demand that keeps a floor under tenant numbers.
What that means for you practically is that the stock competing for tenants is limited, but so is the stock competing for buyers. We work through which suburbs are supported by employment rather than speculation, and where the flood and insurance exposure quietly erodes the yield the listing advertises.
Rent, Structure And Holding Cost Questions
How much of the rent will a lender count?
Not all of it. Most lenders discount rental income to allow for vacancy and costs, and how much they discount varies enough to change the outcome. We check the shortlist against your specific figures rather than assuming a standard treatment.
Should I go interest-only?
It depends on whether you need the cash flow now or the debt reduction later, and on what else you plan to buy. Interest-only preserves cash flow and can suit an investment purpose, but the repayments step up when the period ends and some lenders assess you more harshly for it. We model both before you choose.
Is a DHA leaseback property a good investment?
It suits investors who want guaranteed rent and no management, and it costs you a higher management fee, control during the lease, and a narrower resale market later. Some lenders also treat them differently. We run the comparison against a standard purchase so you can see the difference rather than take the pitch at face value.
How much should I budget for insurance in Townsville?
Get a quote on the actual address before you commit. Northern Queensland premiums run well above the national average because of cyclone exposure, and a flood overlay can push a property from expensive to uninsurable with some providers. It is the most common reason a local investment misses its projected return.
About us
Who Structures the Portfolio
The person who answers reads your existing loans before your next listing. What is already in place decides more about the purchase you are planning than the property does, and it is not visible from the outside.
Getting the structure right is worth more than shaving the rate, because it decides whether there is a purchase after this one.
-
Call
Monday to Friday, 9am to 5pm
-
Use the form
Better if you are on shift or on site and cannot talk
-
Email
info@mortgagebrokertownsville.net.au
Useful if you already have documents to hand over
-
Where we are
Townsville, QLD 4810
The city, the northern beaches and the districts inland
Get Your Townsville Investment Structured
If you already hold a property, bring the existing loans as well. What is already in place decides more about the next purchase than the listing does.
Call (07) 4463 8031 Use The Form
Prefer to start from the beginning? Our Mortgage Broker Townsville page covers what we do and how we are paid.