
Buying
Home Loans Townsville
The figure a bank website gives you is not the figure it will lend you. Every lender has to test you at three percentage points above the rate you would actually pay, and that one rule is why most people are approved for less than they expected.
We arrange home loans Townsville wide, and we model your capacity at that assessed rate from the first conversation rather than the advertised one. If the number lands lower than you hoped, it is usually a credit card limit or the wrong lender for your income type, and both of those move.
Talk To a Mortgage Broker in Townsville
Where you are up to, roughly what you have saved, and what you are hoping to buy.
What We Do For You
We work out what you can borrow, then place you with the lender whose credit policy fits your income rather than the one with the best headline rate. That covers first home buyers, upgraders, and anyone whose pay does not arrive as a simple fortnightly salary.
It costs you nothing. The lender pays us a commission when your loan settles, so the conversation, the comparison and the application are free whether or not you go ahead. If the answer is that you should wait six months and reduce a card limit first, that is the answer you get.
Getting To Pre-Approval
Most people come to us before they have found a property, which is the right time. Here is what happens after you make contact.
-
We talk through your situation
Income, deposit, debts, and what you want to buy. That is usually enough to know whether the plan works before anyone fills in a form.
Day one
-
We model it at the assessment rate
A real borrowing number modelled at the assessment rate, not the advertised one, plus the lenders whose policy suits your income type. Have your payslips, bank statements and a list of your debts ready and this moves faster.
-
We lodge for pre-approval
We prepare the application, chase the lender, and handle the questions that come back so you are not doing it. Timeframes vary by lender and by how clean the file is.
Usually a few days to a fortnight
-
You bid knowing your ceiling
Once approval is formal we stay on the file to settlement, including the valuation and any conditions the lender attaches.
Through to settlement
Before You Get In Touch
What do you need from me to get started?
Payslips or tax returns, recent bank and credit card statements, ID, and a rough idea of your deposit and what you want to buy. If you do not have all of it, start with a conversation, because your income and deposit alone are enough for a useful indication.
How long does pre-approval take?
Formal pre-approval from the lender usually takes anywhere from a few days to a couple of weeks, depending on which lender it is and how complete the paperwork is when it goes in. A clean file with payslips, statements and identification all present moves at the shorter end of that.
Does using a broker cost me anything?
No. We are paid a commission by the lender when your loan settles. There is no fee to you in a standard residential loan, and no charge for the conversation if you decide not to proceed.
How Much You Can Borrow in Townsville
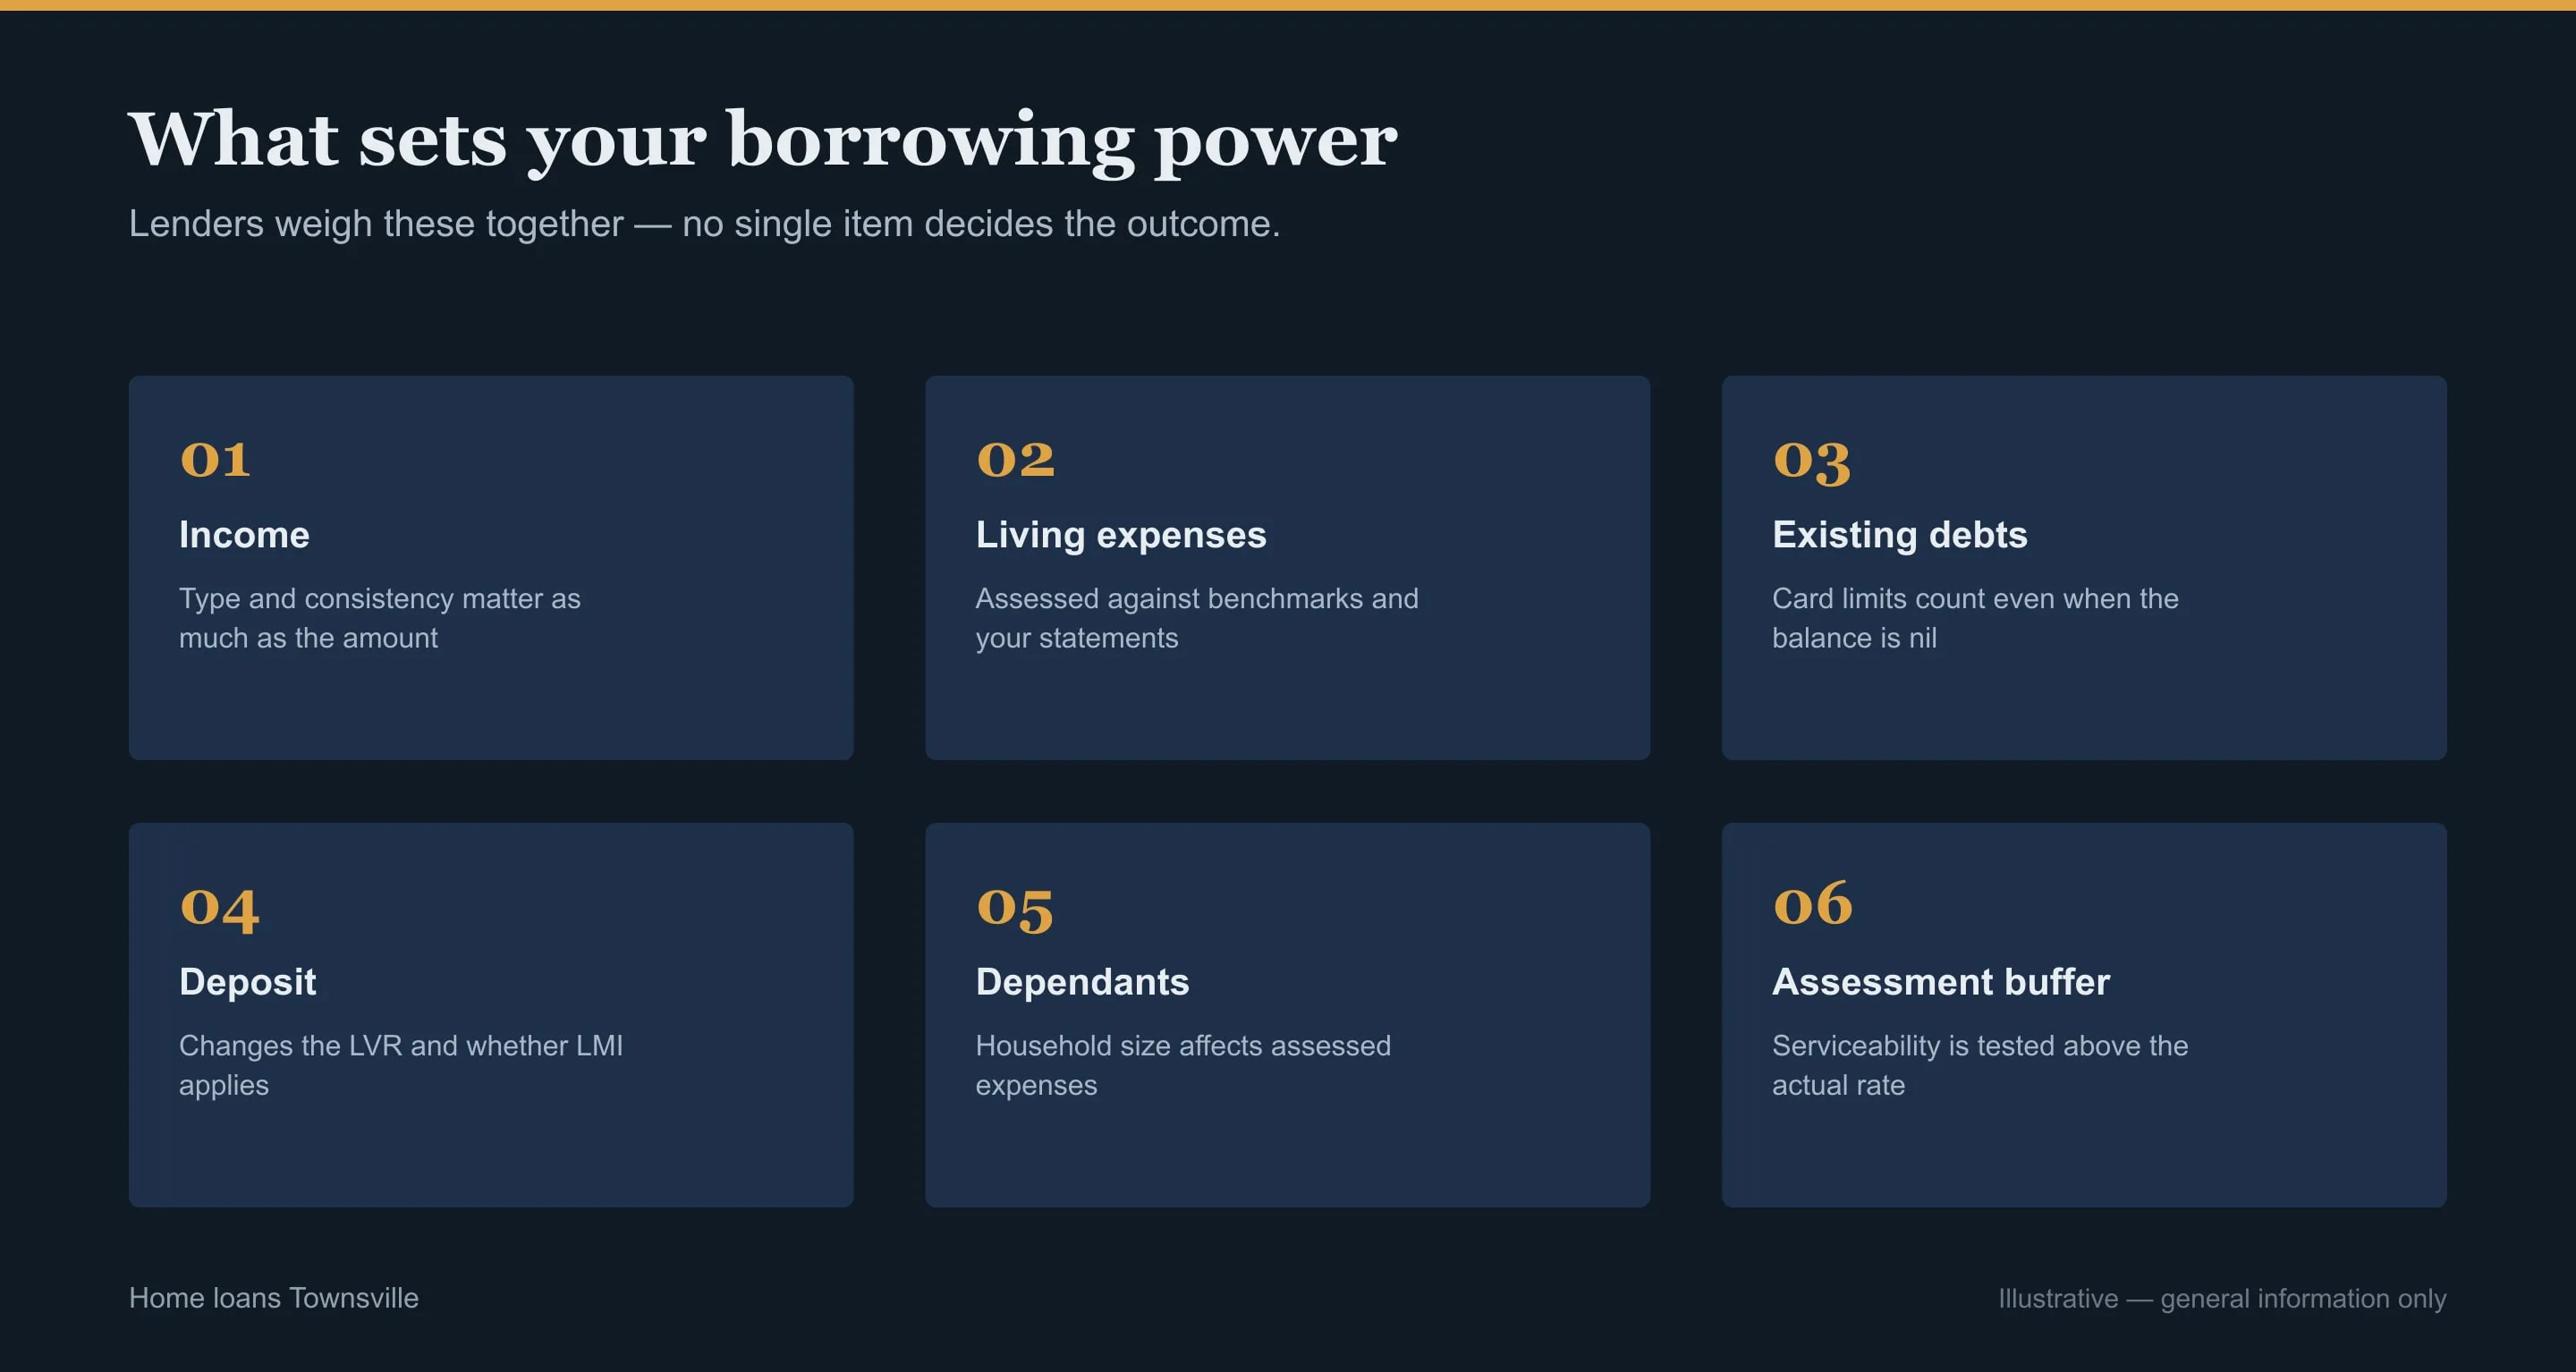
Every lender has to test you at three percentage points above the rate you would actually pay. That is APRA’s serviceability buffer, and it is the single biggest reason people are approved for less than they expect. We model your capacity at the assessed rate from the first conversation, so the figure we give you is the one a lender will land on rather than a best case that falls over at application.
Your credit cards are read the same way. A lender counts the full limit against you regardless of what you owe on it, so a card sitting at zero with a large limit still eats into what you can borrow. We go through your limits before anything is lodged and tell you which ones to reduce or close, because that is often the fastest way to move your number up.
Declared living expenses get floored too. Lenders apply the Household Expenditure Measure benchmark, so writing down an unrealistically low number does not help you, because it just gets replaced. We work from the benchmark up, which means fewer surprises when the assessor reads the file.
Where The Debt-To-Income Cap Bites
From 1 February 2026 APRA limits how much a lender can write at six times income or above to twenty per cent of its new loans, with owner-occupier and investor books measured separately each quarter. In practice that means a lender near its quarterly limit gets fussier about high-DTI files, and the same application can succeed at one bank and stall at another.
Two exemptions matter here. Loans for new dwellings are outside the cap, as are owner-occupier bridging loans. If your DTI is close to the line, building rather than buying established can change which lenders will look at you, so we check that before you commit to a property type.
Buying With a Small Deposit
Above eighty per cent of the property value, Lenders Mortgage Insurance kicks in and you pay for a policy that protects the bank rather than you. The First Home Guarantee is the way around it: five per cent deposit, no LMI, with Housing Australia guaranteeing up to fifteen per cent of the value to the lender.
Since 1 October 2025 that scheme has no income caps and unlimited places, so the old $125,000 and $200,000 income thresholds you may still find quoted online no longer apply. The constraint that does still apply is the price cap, and it is where most Townsville buyers get caught out.
Scheme thresholds change. We confirm the current figures against your situation before you rely on any of them.
What Your Deposit Actually Buys Here
The $700,000 cap is frequently reported as a million dollars, because that is the figure attached to the Gold Coast and the Sunshine Coast. They are the only two locations in Queensland holding the higher cap. Townsville sits under the $700,000 "other areas" cap, and buying a cent above it puts you outside the Guarantee entirely.
That cap still works here, which is the good news and the reason to move. The house median sits somewhere in the high-$500,000s to high-$600,000s depending on which boundary you measure. CoreLogic had Townsville City at $560,000 in April 2026, while broader council-area measures run closer to $685,000 to $695,000. Either way most established houses remain under the cap, and the gap is narrowing rather than widening.
We check the cap against the specific suburbs and price bracket you are looking at before you start inspecting, because it decides which properties are even in play for you. Where the stock you want is bumping the cap, we will say so early rather than after a failed offer.
Why Valuations Come In Low Here
Townsville was flat or falling for years after the resources downturn, then grew quickly. Valuers who lived through that remain cautious, and in a fast-moving market a valuation can land at or below what you agreed to pay. The lender lends against the valuation, not the contract, so a shortfall becomes deposit you have to find.
We flag that risk before you sign, and where a property looks like a valuation problem we structure the finance clause to give you room rather than leaving you exposed to it.
Borrowing And Deposit Questions
Is the $700,000 cap enough to buy in Townsville?
For most established houses, yes. The house median sits in the high-$500,000s to high-$600,000s depending on the boundary measured, so the majority of local stock is still under the First Home Guarantee cap, but the margin is shrinking, which is an argument for acting sooner rather than later.
Can I use the First Home Guarantee if I earn a high income?
Yes. The income caps were removed on 1 October 2025 and places are unlimited. Older articles still quoting a $125,000 single or $200,000 couple limit are out of date. The price cap on the property still applies.
Should I pay down my credit card before applying?
Reducing the limit matters more than reducing the balance, because lenders assess the full limit regardless of what is owing. We look at your limits early and tell you which ones are worth cutting, since it is often the quickest way to lift your borrowing capacity.
About us
Who Works On Your Application
The person who answers the phone is the person who models your capacity and writes the application. It is not passed to a processing team once you agree to proceed, which is what decides how quickly a question gets answered when a lender raises one.
Most of the files here turn on how income is read rather than how much of it there is. Allowances, roster pay, contract income and a business return all get treated differently by different lenders, and that is the part worth having someone stay on.
-
Call
Monday to Friday, 9am to 5pm
-
Use the form
Better if you are on shift or on site and cannot talk
-
Email
info@mortgagebrokertownsville.net.au
Useful if you already have documents to hand over
-
Where we are
Townsville, QLD 4810
The city, the northern beaches and the districts inland
Talk To a Mortgage Broker in Townsville
If you are still working out whether the numbers stack up at all, that is the normal place to start rather than a reason to wait.
Call (07) 4463 8031 Use The Form
Prefer to start from the beginning? Our Mortgage Broker Townsville page covers what we do and how we are paid.