
Refinancing
Refinancing Townsville
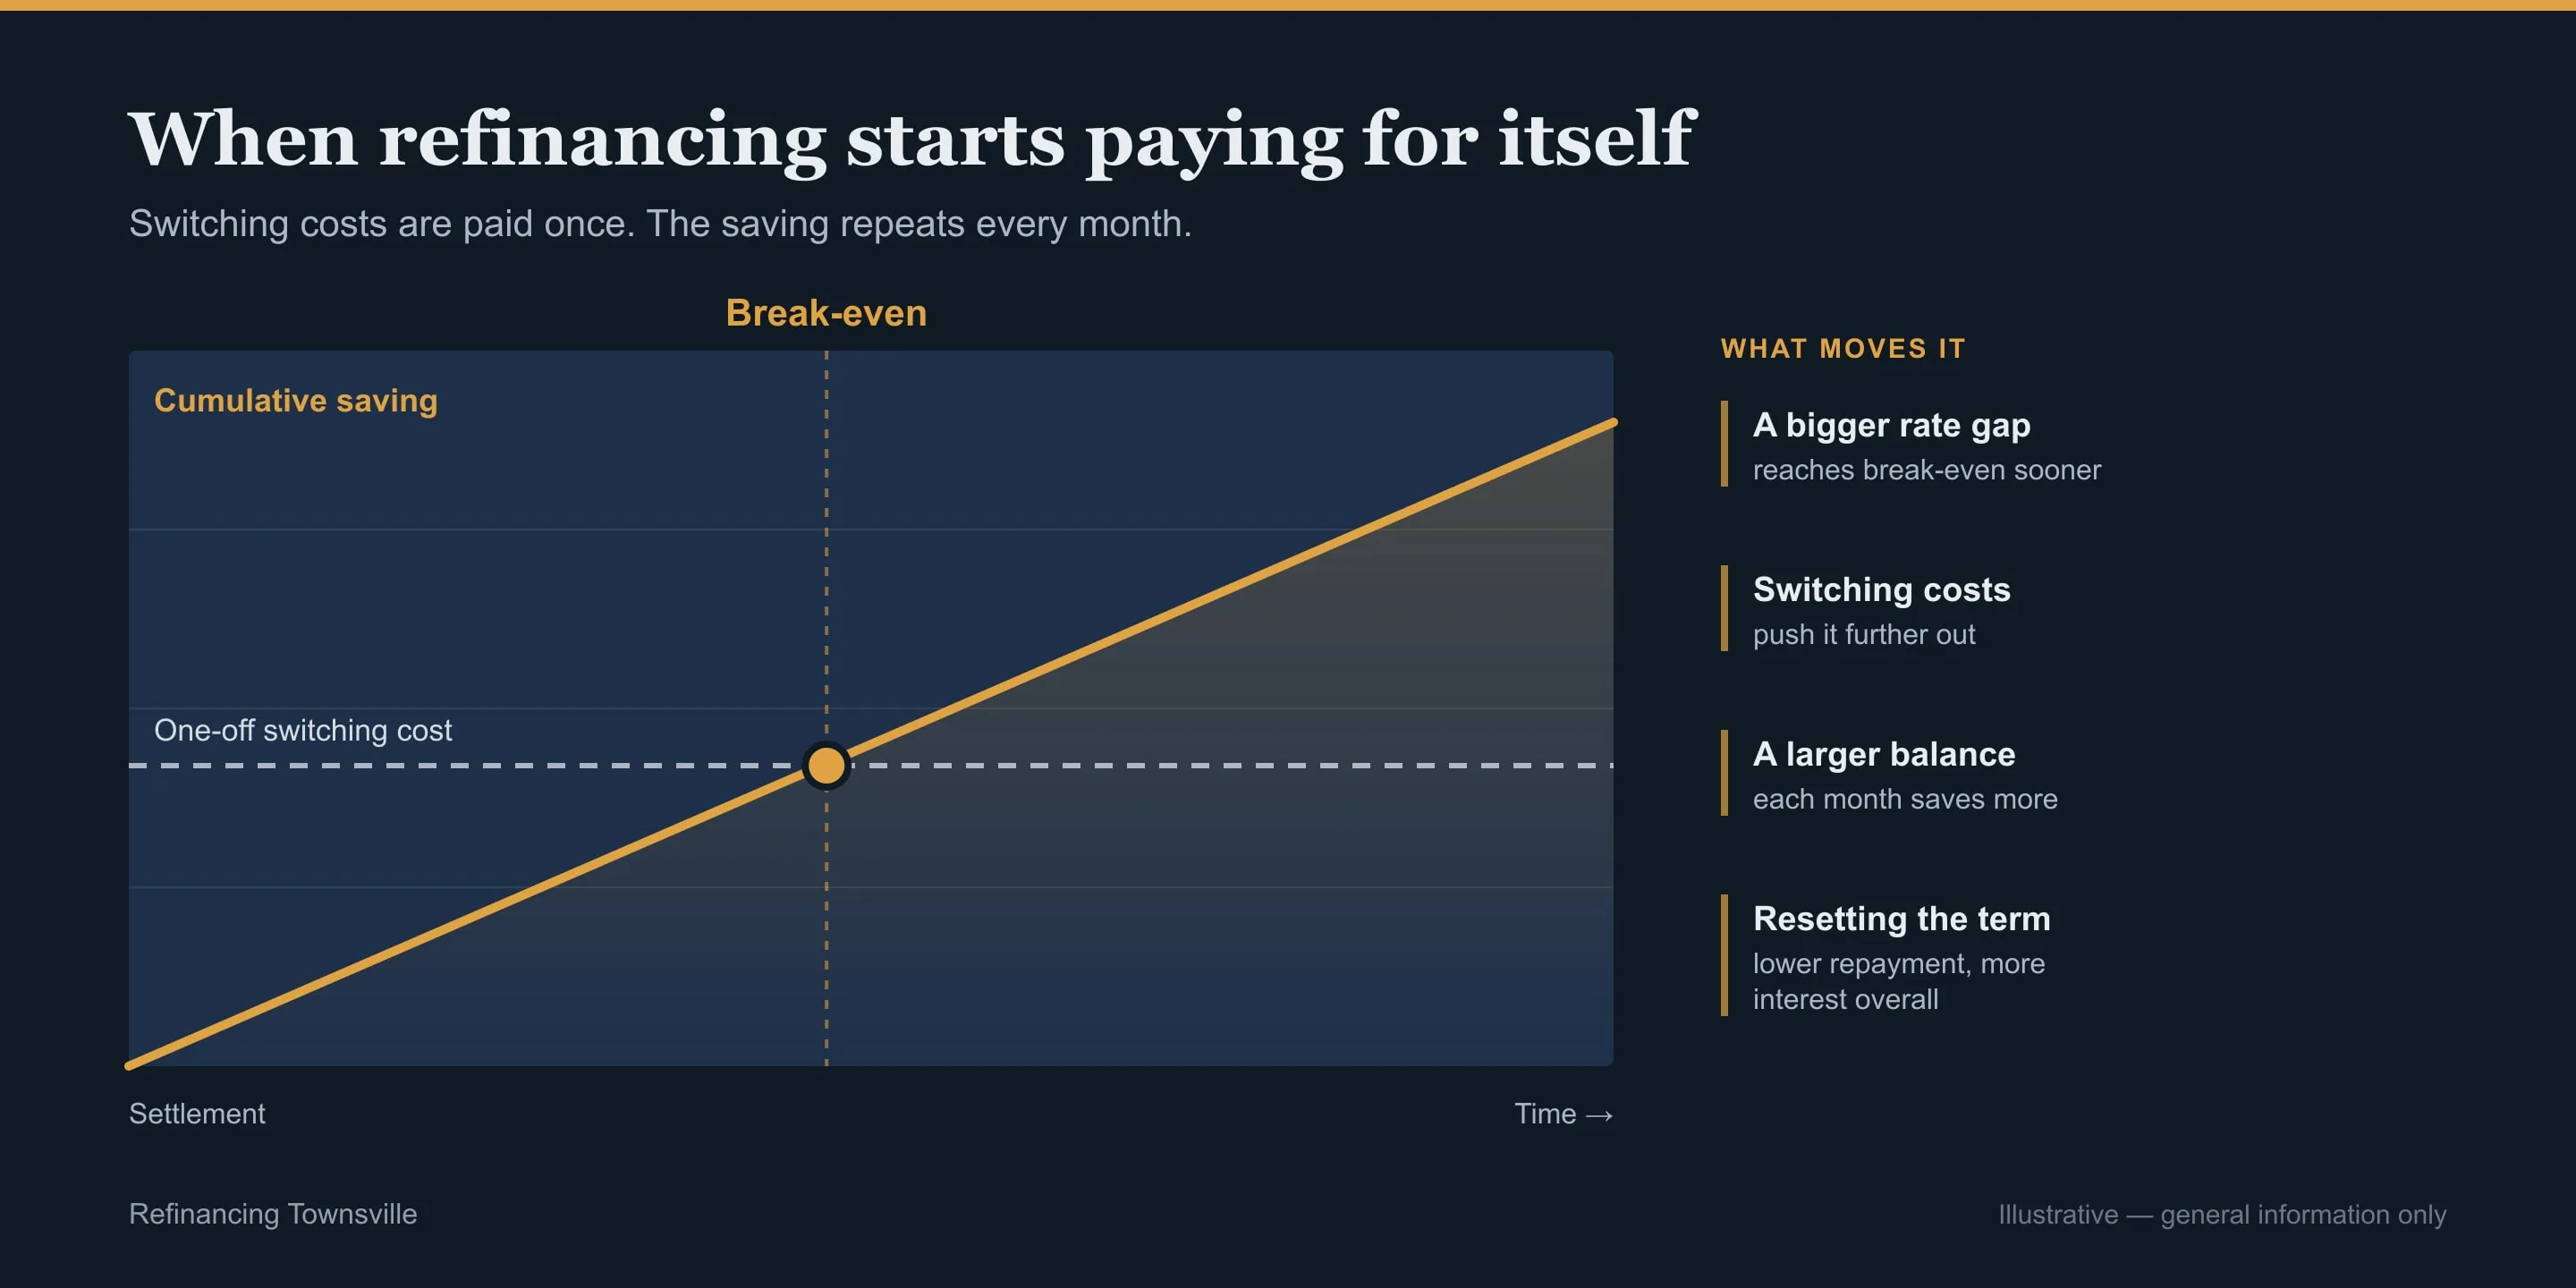
A lower rate is not the same as saving money. Discharge and registration fees, a fresh application, and Lenders Mortgage Insurance charged a second time can all outrun the gap you are switching for, and none of them show up in an advertised comparison.
We handle refinancing Townsville wide, and the review runs both directions: what you could move to, set against what leaving actually costs. Where the numbers say stay put, that is the answer you get.
Get Your Home Loan Reviewed in Townsville
Who you are with now, roughly what is owing, and what the place is worth.
What The Review Covers
We compare your current loan against what you could move to, cost the switch in full, and handle the move if it is worth making. That covers a straight rate reduction, rolling other debt into the loan, releasing equity, and restructuring after a change in income.
It costs you nothing either way. We are paid a commission by the lender only if a loan settles, so a review that ends with you staying where you are is free, and it ends that way often enough to be worth saying up front.
How a Refinance Runs
Most of this happens without you needing to take time off. Have your last two loan statements and a recent payslip handy and it moves quickly.
-
We look at what you have now
Your current balance, rate, structure and any fixed portion or offset. This is also where we find out whether your existing lender will simply match a better offer, which is sometimes the easiest win available.
Day one
-
We work out if the switch stands up
What you could move to, against what leaving costs: discharge, registration, application and possibly LMI again. The case for staying is part of that comparison, not a footnote to it.
-
We lodge with the lender most likely to approve you
Not just the sharpest offer on paper. The one whose serviceability policy actually fits your income, so the application does not stall at assessment.
Once you decide
-
We manage the discharge and settlement
The new lender pays out the old one and the title transfers. We coordinate both sides and chase the discharge, which is the part that usually causes the delay.
Typically a few weeks
Before You Get In Touch
What do you need from me to review my loan?
Your last two home loan statements, a recent payslip or two, and a rough idea of what your property is worth. That is enough to tell you whether switching is worth pursuing before you fill in anything.
How long does refinancing take?
Usually a few weeks from application to settlement. The variable part is your current lender releasing the mortgage, which is outside both our control and the new lender’s. We chase it, but it is the step most likely to add time.
Does the review cost me anything?
No. We are paid a commission by the new lender when a loan settles. If we tell you to stay where you are, we are not paid, and the review still costs you nothing.
When Refinancing Is Not Worth It
Plenty of the reviews we do end with a recommendation to stay. If you are part-way through a fixed term, break costs can wipe out years of savings. If your balance is small or nearly paid down, the switching costs may never be recovered. And if you refinanced recently, there may simply be nothing on the market far enough ahead to justify moving again.
We are required to act in your best interests, and that duty cuts both ways, so it means telling you when the answer is no. Being told to stay put is a legitimate outcome here rather than a wasted conversation.
The other outcome worth knowing about is that your current lender matches. Retention pricing is real, and a credible move elsewhere is often what prompts it. We will tell you when that is the likely play.
The Buffer That Traps You Where You Are
Every lender must assess you at three percentage points above the rate you would actually pay. That applies to a refinance the same as a new purchase, which produces the situation people find genuinely absurd: you can be meeting your current repayments comfortably, apply to move to a cheaper loan, and be declined because you do not service the cheaper loan at the buffered rate.
If that is you, you are not stuck. Some lenders apply a modified assessment to a straight like-for-like refinance, meaning the same balance, the same term and no cash out, precisely because the switch reduces your risk rather than increasing it. It is not offered by everyone and it is not automatic, so which lender you approach decides whether it is even on the table.
That is the part we do. We know which lenders will consider a streamlined assessment and what conditions they attach, and we structure the application to fit it rather than sending you at a bank that will reject you on a technicality. If nothing fits, we tell you what to change, usually credit card limits or a small personal debt, and how long it takes to move the number.
What Leaving Your Lender Costs
A refinance is not free, and any comparison that ignores the exit is not a comparison. There is a discharge fee from your current lender, a government mortgage registration and release fee, usually an application or settlement fee at the new lender, and a break cost if any portion of your loan is fixed.
One catches people out more than the rest. If your loan is above eighty per cent of what the property is currently worth, the new lender will require Lenders Mortgage Insurance even if you already paid it once with your existing lender. It is not transferable and it is not refundable. For a borrower who bought with a small deposit and has not built much equity since, that single line item can be the whole argument against switching.
We total every one of these against the benefit before you commit to anything, so the decision is made on the net position rather than the headline.
Exit and entry costs are deliberately not priced here, because they vary by lender and by loan. We total yours against the benefit before you decide.
Refinancing To Release Equity
If your property has gained value, refinancing can free some of that equity for a renovation, a deposit on an investment, or consolidating higher-cost debt. Townsville values have moved considerably in recent years, so there are borrowers across the city sitting on more equity than they realise, particularly anyone who bought before the growth.
Two things change when you take cash out. The relaxed like-for-like assessment usually disappears, because the loan is no longer a straight swap. You are borrowing more, so you are assessed on the full amount at the buffered rate. And your debt-to-income ratio rises, which matters more since February 2026 now that lenders ration high-DTI approvals against a quarterly limit.
We check both before you get attached to the plan, and we will tell you if a smaller release gets you under a threshold that a larger one would push you over.
Refinancing After Townsville Values Moved
Values have risen sharply since the years following the resources downturn, and that changes two things for existing borrowers. If you bought with a small deposit and paid LMI, growth may have taken you back under eighty per cent, which means a switch that was uneconomic two years ago may not be now.
The other side is the valuation. A refinance requires the new lender to value your property, and Townsville valuers who worked through the flat years remain conservative. A valuation that comes in under your expectation changes your LVR, which changes your pricing tier and can change whether LMI applies at all. We order it early and structure around the result, rather than building a case on a number that has not been confirmed.
Costs, Timing And Equity Questions
Will you tell me if I should not refinance?
Yes, and it happens regularly. Break costs on a fixed portion, a small remaining balance, or LMI becoming payable again can all mean staying put is the better outcome. We are obliged to act in your best interests, and that includes recommending you do nothing.
Can I refinance if I can barely afford my current repayments?
Possibly, and it is worth asking. The three-point buffer means some borrowers cannot qualify for a cheaper loan than the one they are already paying, but some lenders apply a modified assessment to a straight like-for-like switch. Which lender you approach decides whether that option exists for you.
Do I have to pay LMI again if I switch?
Only if your loan is above eighty per cent of the property’s current value. LMI does not transfer between lenders and is not refundable, so it is a genuine cost of moving. If Townsville growth has lifted your equity past that line since you bought, it may no longer apply.
About us
Who Runs the Comparison
The person who answers builds the comparison, and if the answer is to stay put, tells you that. A fair share of these end with a recommendation to do nothing, which is a normal result of the arithmetic rather than a wasted conversation.
Where a switch does stack up, someone still has to sit on the discharge until it moves. That is the same person you spoke to at the start, not a file number handed to a processing queue.
-
Call
Monday to Friday, 9am to 5pm
-
Use the form
Better if you are on shift or on site and cannot talk
-
Email
info@mortgagebrokertownsville.net.au
Useful if you already have documents to hand over
-
Where we are
Townsville, QLD 4810
The city, the northern beaches and the districts inland
Get Your Home Loan Reviewed in Townsville
If the answer turns out to be that you are better off where you are, that is a result worth having rather than a wasted conversation.
Call (07) 4463 8031 Use The Form
Prefer to start from the beginning? Our Mortgage Broker Townsville page covers what we do and how we are paid.