
Specialist
Rural Home Loans Townsville
The question that decides an acreage purchase is whether a lender still calls it residential. Past a certain land size, or on the wrong zoning, the same block moves to rural lending terms: a larger deposit, a narrower list of lenders, and a valuation that reads the property completely differently.
We arrange rural home loans Townsville and district wide, and that question gets answered from the listing before you are committed to anything. Land size, zoning, access and water all decide it, and none of them are about your income.
Get a Townsville Block Checked
The listing or the address, and the title details if you have them.
What We Establish First
We establish whether the block can be financed on residential terms, identify the lenders that will take it if it cannot, and tell you what deposit that realistically requires. That covers lifestyle blocks, hobby farms and houses on land large enough that a mainstream lender stops treating them as ordinary housing.
The check costs you nothing. We are paid a commission by the lender on settlement, so finding out whether a block is financeable is free, including when the answer is that it is not.
Checking an Acreage Property
On rural property the block decides the loan before your income does. This is the order that avoids a wasted application.
-
We assess the land before the borrower
Size, zoning, title, access and services. Send the listing and the title details. This determines whether we are arranging a residential loan at all, and it is not a question your income can answer.
Day one
-
We shortlist the lenders that take it
Appetite for acreage varies sharply, and the block size where each lender stops is different. We approach the ones whose policy fits rather than testing your credit file at the ones that do not.
-
We set your deposit expectation early
Lenders generally require a larger deposit as land size increases, and some restrict Lenders Mortgage Insurance on rural security entirely. Better to know that before you are bidding.
Before you make an offer
-
We manage the valuation and settlement
Rural valuations take longer, cost more and produce more conditions. We prepare the file accordingly and work through what the valuer raises.
Through to settlement
Before You Get In Touch
What do you need from me to check an acreage property?
The listing and the address to start with, and the title details if you have them. The block size, zoning and access matter more at this stage than your income does, and we can usually give you a position before you provide any financials.
How long does an acreage loan take?
Longer than a suburban purchase, mostly because of the valuation. Rural valuations take more time to arrange and complete, and they raise more conditions. Allow extra time in your finance clause rather than assuming a standard timeframe.
Do you charge for assessing a rural property?
No. The lender pays us a commission when a loan settles. Checking whether a block can be financed costs you nothing, including in the cases where we tell you it cannot.
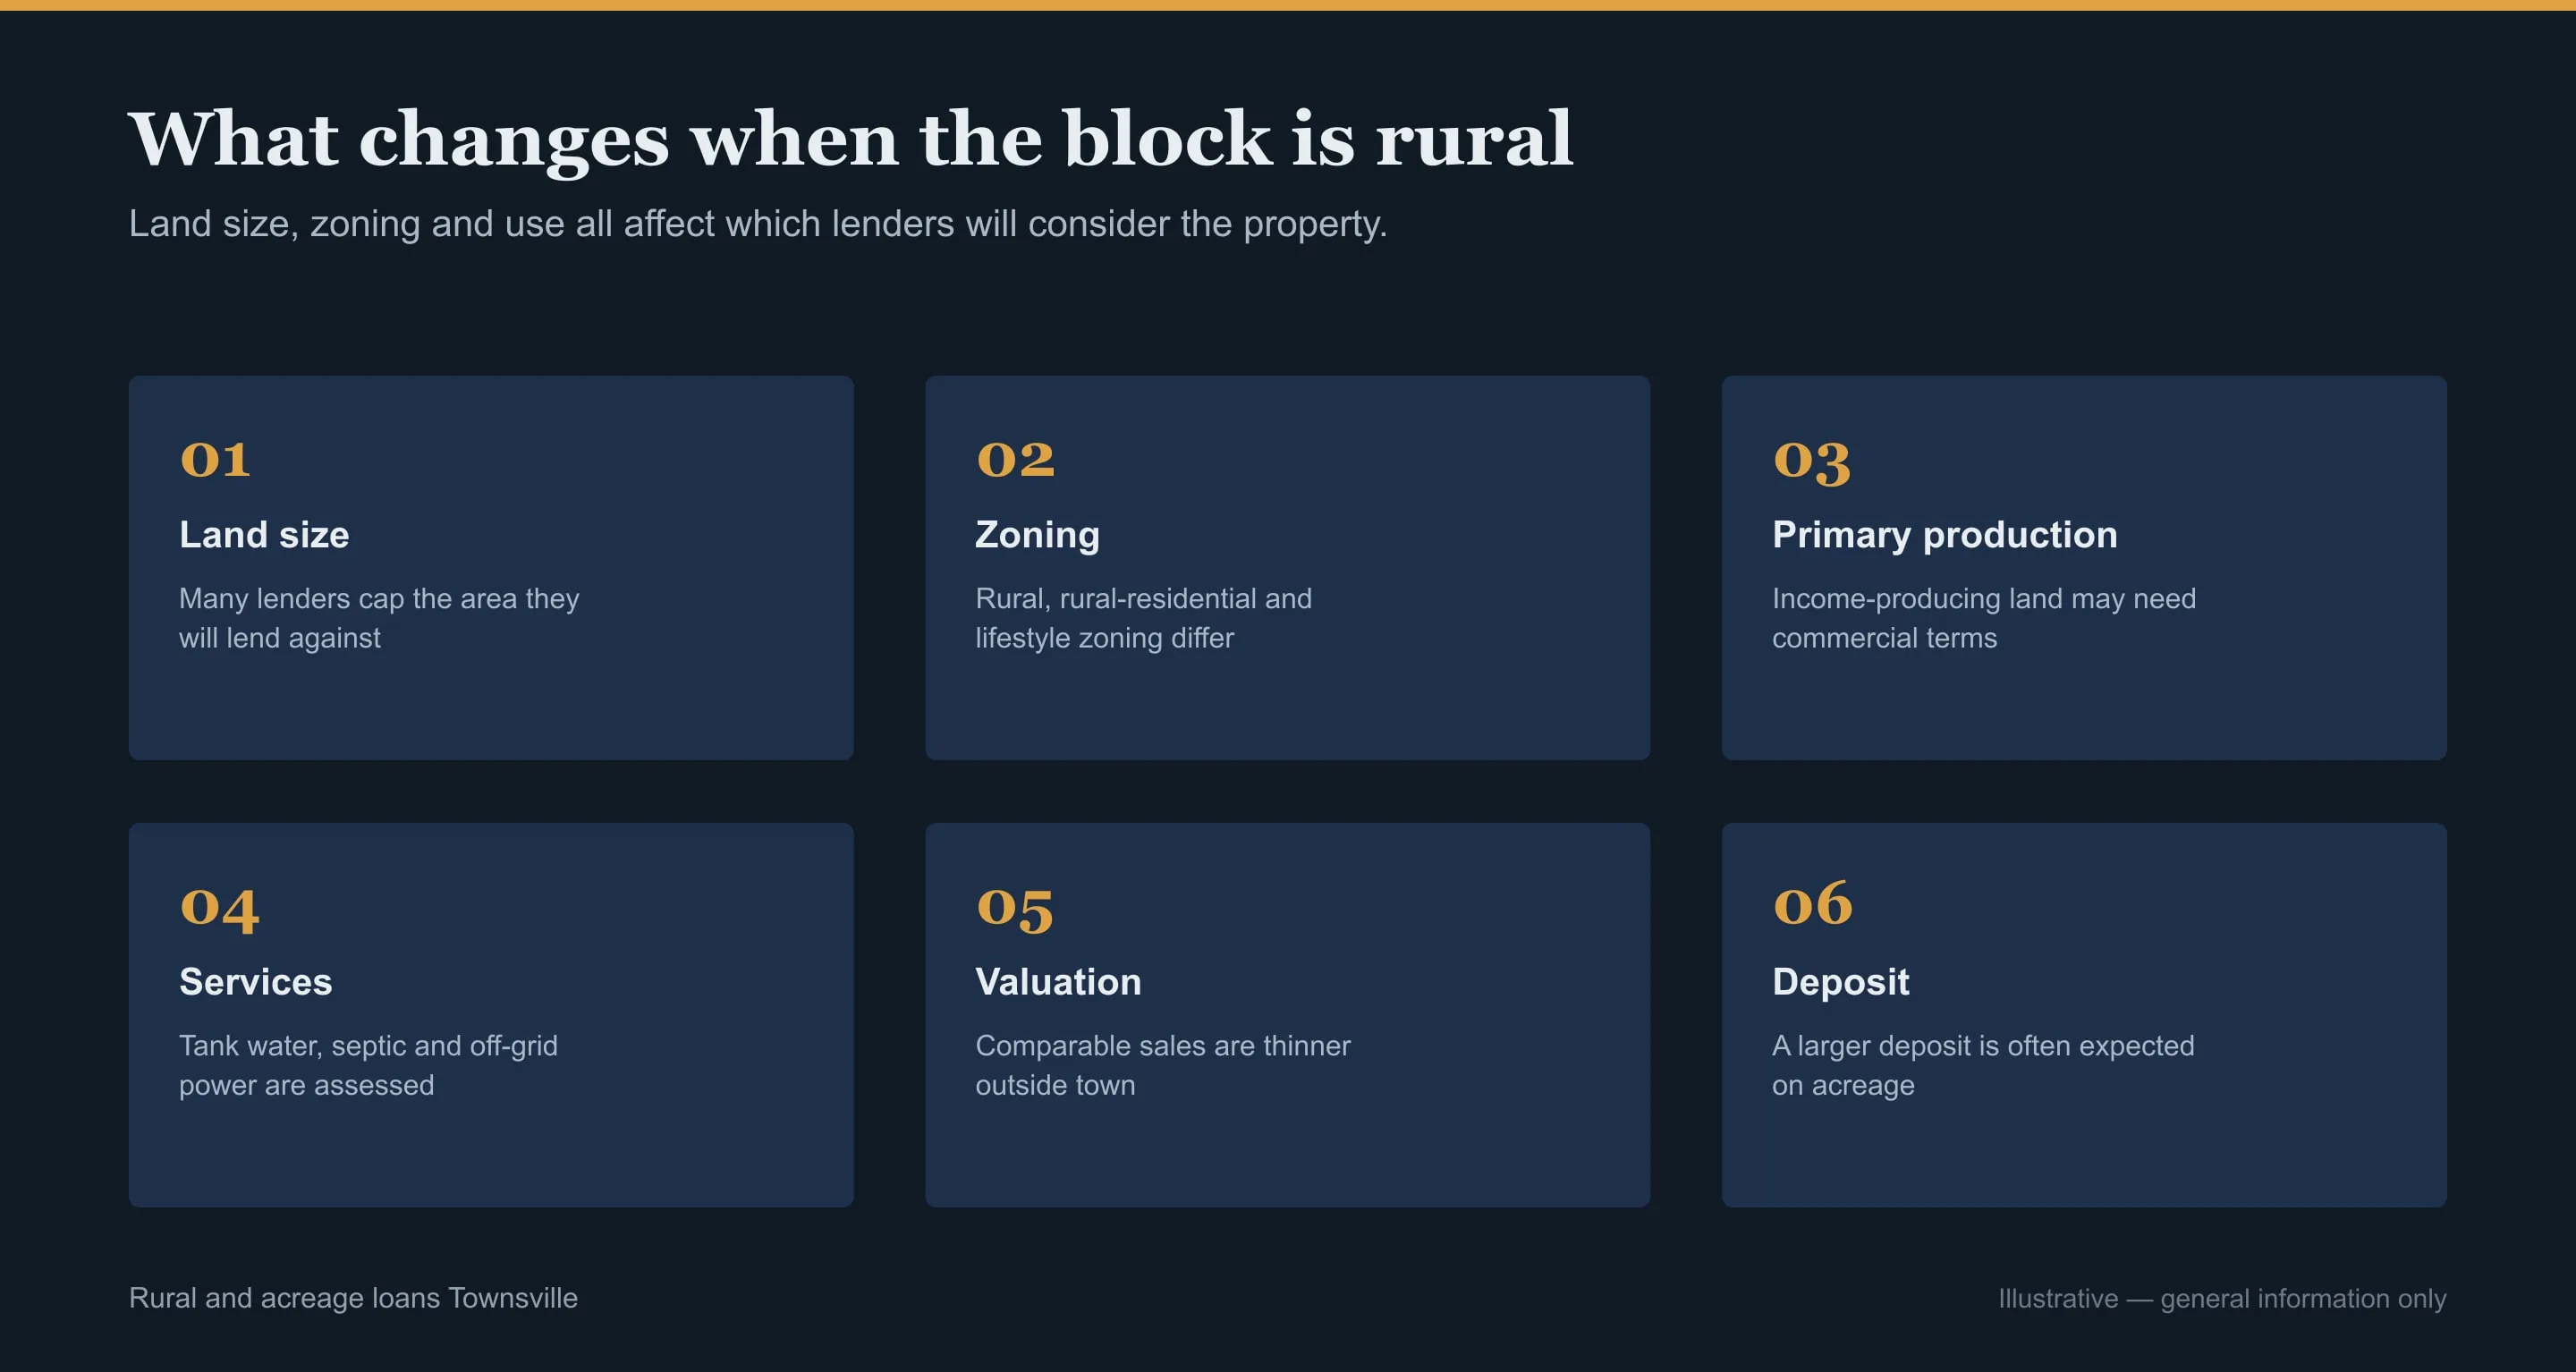
Where Residential Lending Stops
A residential home loan is written against a house on a block. As the block gets larger, lenders start treating the land as the primary asset rather than the dwelling, and at some point they stop calling it residential lending altogether.
There is no single threshold across the industry. Some lenders are comfortable to a few hectares on standard terms, some go considerably further with conditions, and some restrict acreage lending to a much smaller footprint. The practical consequence is that the same property can be a straightforward approval at one bank and outside policy at another, and knowing which is which before you apply is most of the value here.
Beyond residential lending sits agribusiness finance, which is a different product with different assessment, different documentation and different pricing. If your purchase is a genuine working operation rather than a home on land, we will tell you plainly and point you to the right kind of lender rather than forcing a residential application that was never going to work.
How Zoning Changes Your Loan
The zoning on the title matters more than what the property looks like. Rural residential and residential-zoned acreage generally finance as ordinary home loans. Land zoned rural or agricultural, or a property with a primary production classification, moves the file toward commercial or agribusiness assessment even when there is a perfectly normal house on it.
The same applies to income from the land. If part of the property is leased for grazing or produces an agricultural income, that changes how a lender categorises the purchase, and it does not always help you, because income from the land does not necessarily count toward serviceability while the classification it triggers can restrict your options.
We check the zoning and the title before anything is lodged, because it is the variable that most often turns an apparently simple purchase into a decline.
What a Valuer Looks For On Acreage
Rural valuations are slower, more expensive and more conditional than suburban ones, and they turn on things that never come up in town. Whether the access is a sealed road, an unsealed council road or an easement across a neighbour’s land. Whether water is mains, a bore or tank supply, and whether the bore has been tested. Whether power is connected or the property runs on solar and a generator.
The other issue is what the improvements are worth. A large shed, an arena or extensive fencing may have cost the current owner a great deal and add very little to a valuation, because the valuer is assessing the dwelling and the land rather than the total spend. That gap becomes deposit you have to find, and it is the most common reason an acreage purchase falls over between contract and settlement.
We flag those risks against the specific listing before you sign, and where the numbers look tight we structure the finance clause so a low valuation is something you can walk away from rather than something you have to fund.
Land size and LVR thresholds are deliberately not given as numbers. They vary too much between lenders for a general figure to be useful, and we confirm the current position for your block.
Buying Acreage Around Townsville
The lifestyle blocks sit in the districts west and south of the city, close enough to Townsville to commute and far enough out that the block sizes change what a lender will do. Out toward Hervey Range the blocks run large enough that some lenders stop calling it residential lending at all. The appeal is obvious: space, no neighbours, and land at a price that would buy a suburban courtyard further south.
What to establish before you commit is unglamorous. How the property is accessed in the wet season, whether the water supply is reliable through a dry year, and what insurance costs given the cyclone exposure Townsville carries and a block with no immediate neighbours. Each affects either the valuation or the insurability, and insurability decides the loan.
We tell you which of them apply to the specific property you are looking at, so you are checking the things that actually decide the finance rather than everything at once.
Land Size, Zoning And Deposit Questions
How big a block can I buy on a normal home loan?
It depends entirely on the lender, because there is no industry threshold. Some stop at a few hectares, others go well beyond with conditions attached. That variation is why we check policy against your specific block before approaching anyone.
Will I need a bigger deposit for acreage?
Usually. Lenders generally require more equity as land size increases, and many restrict Lenders Mortgage Insurance on rural security, which removes the low-deposit path you would have in town. We set that expectation before you start making offers.
Can you help if it is a working farm rather than a lifestyle block?
That is agribusiness lending rather than a home loan, and it is a different product with different assessment. We will tell you straight away if that is what your purchase is, so you are talking to the right kind of lender instead of collecting declines from residential ones.
About us
Who Checks the Block First
The person who answers has read enough titles to know which questions to ask about a block before anyone opens a calculator. That order is the whole method, and it is why an acreage file rarely gets to the wrong lender here.
It also means telling you when a purchase is agribusiness rather than a home loan, which is a shorter conversation than most people expect and a more useful one than a residential application that was never going to work.
-
Call
Monday to Friday, 9am to 5pm
-
Use the form
Better if you are on shift or on site and cannot talk
-
Email
info@mortgagebrokertownsville.net.au
Useful if you already have documents to hand over
-
Where we are
Townsville, QLD 4810
The city, the northern beaches and the districts inland
Get a Townsville Block Checked
If you have found a block and want to know whether it finances at all, that is the question to settle before the contract, not after it.
Call (07) 4463 8031 Use The Form
Prefer to start from the beginning? Our Mortgage Broker Townsville page covers what we do and how we are paid.