
Buying
First Home Buyer Grants Townsville
Your First Home Guarantee price cap here is $700,000, not the $1,000,000 figure that turns up in national coverage. The higher cap applies to the Gold Coast and the Sunshine Coast and nowhere else in Queensland, and buying above it costs you the scheme entirely.
We sort out which first home buyer grants Townsville buyers can actually claim, then build the loan around them. Which schemes you qualify for, which of them stack, and what each one asks of you after settlement as well as before it.
Find Out What You Qualify For in Townsville
Roughly what you earn, what you have saved, and whether you are looking at new or established.
Where We Come Into It
We check which grants, guarantees and duty concessions you qualify for, work out what each is worth against the specific property you are looking at, then coordinate the lender and your solicitor so the claims land together at settlement. Three different bodies administer these schemes and none of them talk to each other, which is where most of the work goes.
It costs you nothing. The lender pays us a commission when your loan settles, so the eligibility check and the applications are free, including where the answer turns out to be that a scheme does not apply to you.
Claiming What You Are Entitled To
Most of these schemes are claimed through your lender or your solicitor rather than by you directly, and the sequence matters. Getting it wrong can cost you the entitlement.
-
We check which schemes fit you
Your income, deposit, citizenship or residency, prior property ownership and what you plan to buy. Some schemes combine and some are mutually exclusive, and that decides what you should be looking at.
Day one
-
We work out what the property type changes
New, established or vacant land produces very different entitlements in Queensland. Have a price bracket and a suburb in mind and we can be specific rather than general.
-
We prepare and lodge the applications
The grant is usually claimed through your lender at settlement. The duty concession goes through your solicitor. We coordinate both so neither is missed or lodged late.
With the loan application
-
We make sure it lands at settlement
Grant funds are applied at settlement rather than paid to you in advance, so the timing has to work with your deposit. We check that before you commit to a contract date.
Through to settlement
Before You Get In Touch
What do you need from me to check what I qualify for?
Your income, your deposit, whether you or your partner have owned property in Australia before, and your residency status. A rough idea of what you want to buy helps, because the property type decides most of the answer in Queensland.
Do I apply for the schemes myself?
Mostly not. The First Home Owner Grant is usually lodged through your lender with the loan, the transfer duty concession is claimed by your solicitor at settlement, and the First Home Guarantee place is reserved by the lender. We coordinate the three so they land together rather than leaving you to chase each one.
Do you charge for helping with the grant applications?
No. The lender pays us a commission when your loan settles. There is no fee for the eligibility check or for preparing the applications, and no charge if you decide not to buy.
What You Can Actually Claim
Queensland runs two schemes and the Commonwealth runs a third, and they are frequently confused with each other. The First Home Owner Grant is a cash amount, the transfer duty concession is a tax saving, and the First Home Guarantee is a deposit scheme. They are separate, they have different rules, and eligible buyers can hold more than one at the same time.
The grant is the one with the tightest condition. It applies only to a new home, meaning one that has not been lived in before, or to a home you build. If you are buying an established house in Townsville, you do not get it, no matter how good your circumstances are. That single rule redirects more Townsville buyers than any other, and it is worth knowing before you start inspecting rather than after you have made an offer.
Figures are the published Queensland and Commonwealth amounts and change with government policy. We confirm the current position against your circumstances before you rely on any of them. The Queensland Revenue Office and Housing Australia determine eligibility, not us.
The Duty Concession Most Buyers Underestimate
Transfer duty is usually the largest single cost of buying after the deposit, and Queensland removed it entirely for eligible first home buyers purchasing a new home or vacant land to build on from 1 May 2025. There is no value cap on that abolition, which makes it more generous than the grant it sits alongside.
If you are buying an established home instead, you are not left with nothing, because the first home concession still reduces the duty payable, with the relief scaling down as the price rises. It is a smaller benefit than the new-build position but it is real money, and it is claimed through your solicitor rather than automatically applied.
We work out which concession applies to the specific property you are considering and tell your solicitor what to lodge. Where the difference between an established purchase and a new build is close, the duty position is often what tips it, and we will put both numbers in front of you before you decide.
Stacking The Schemes Together
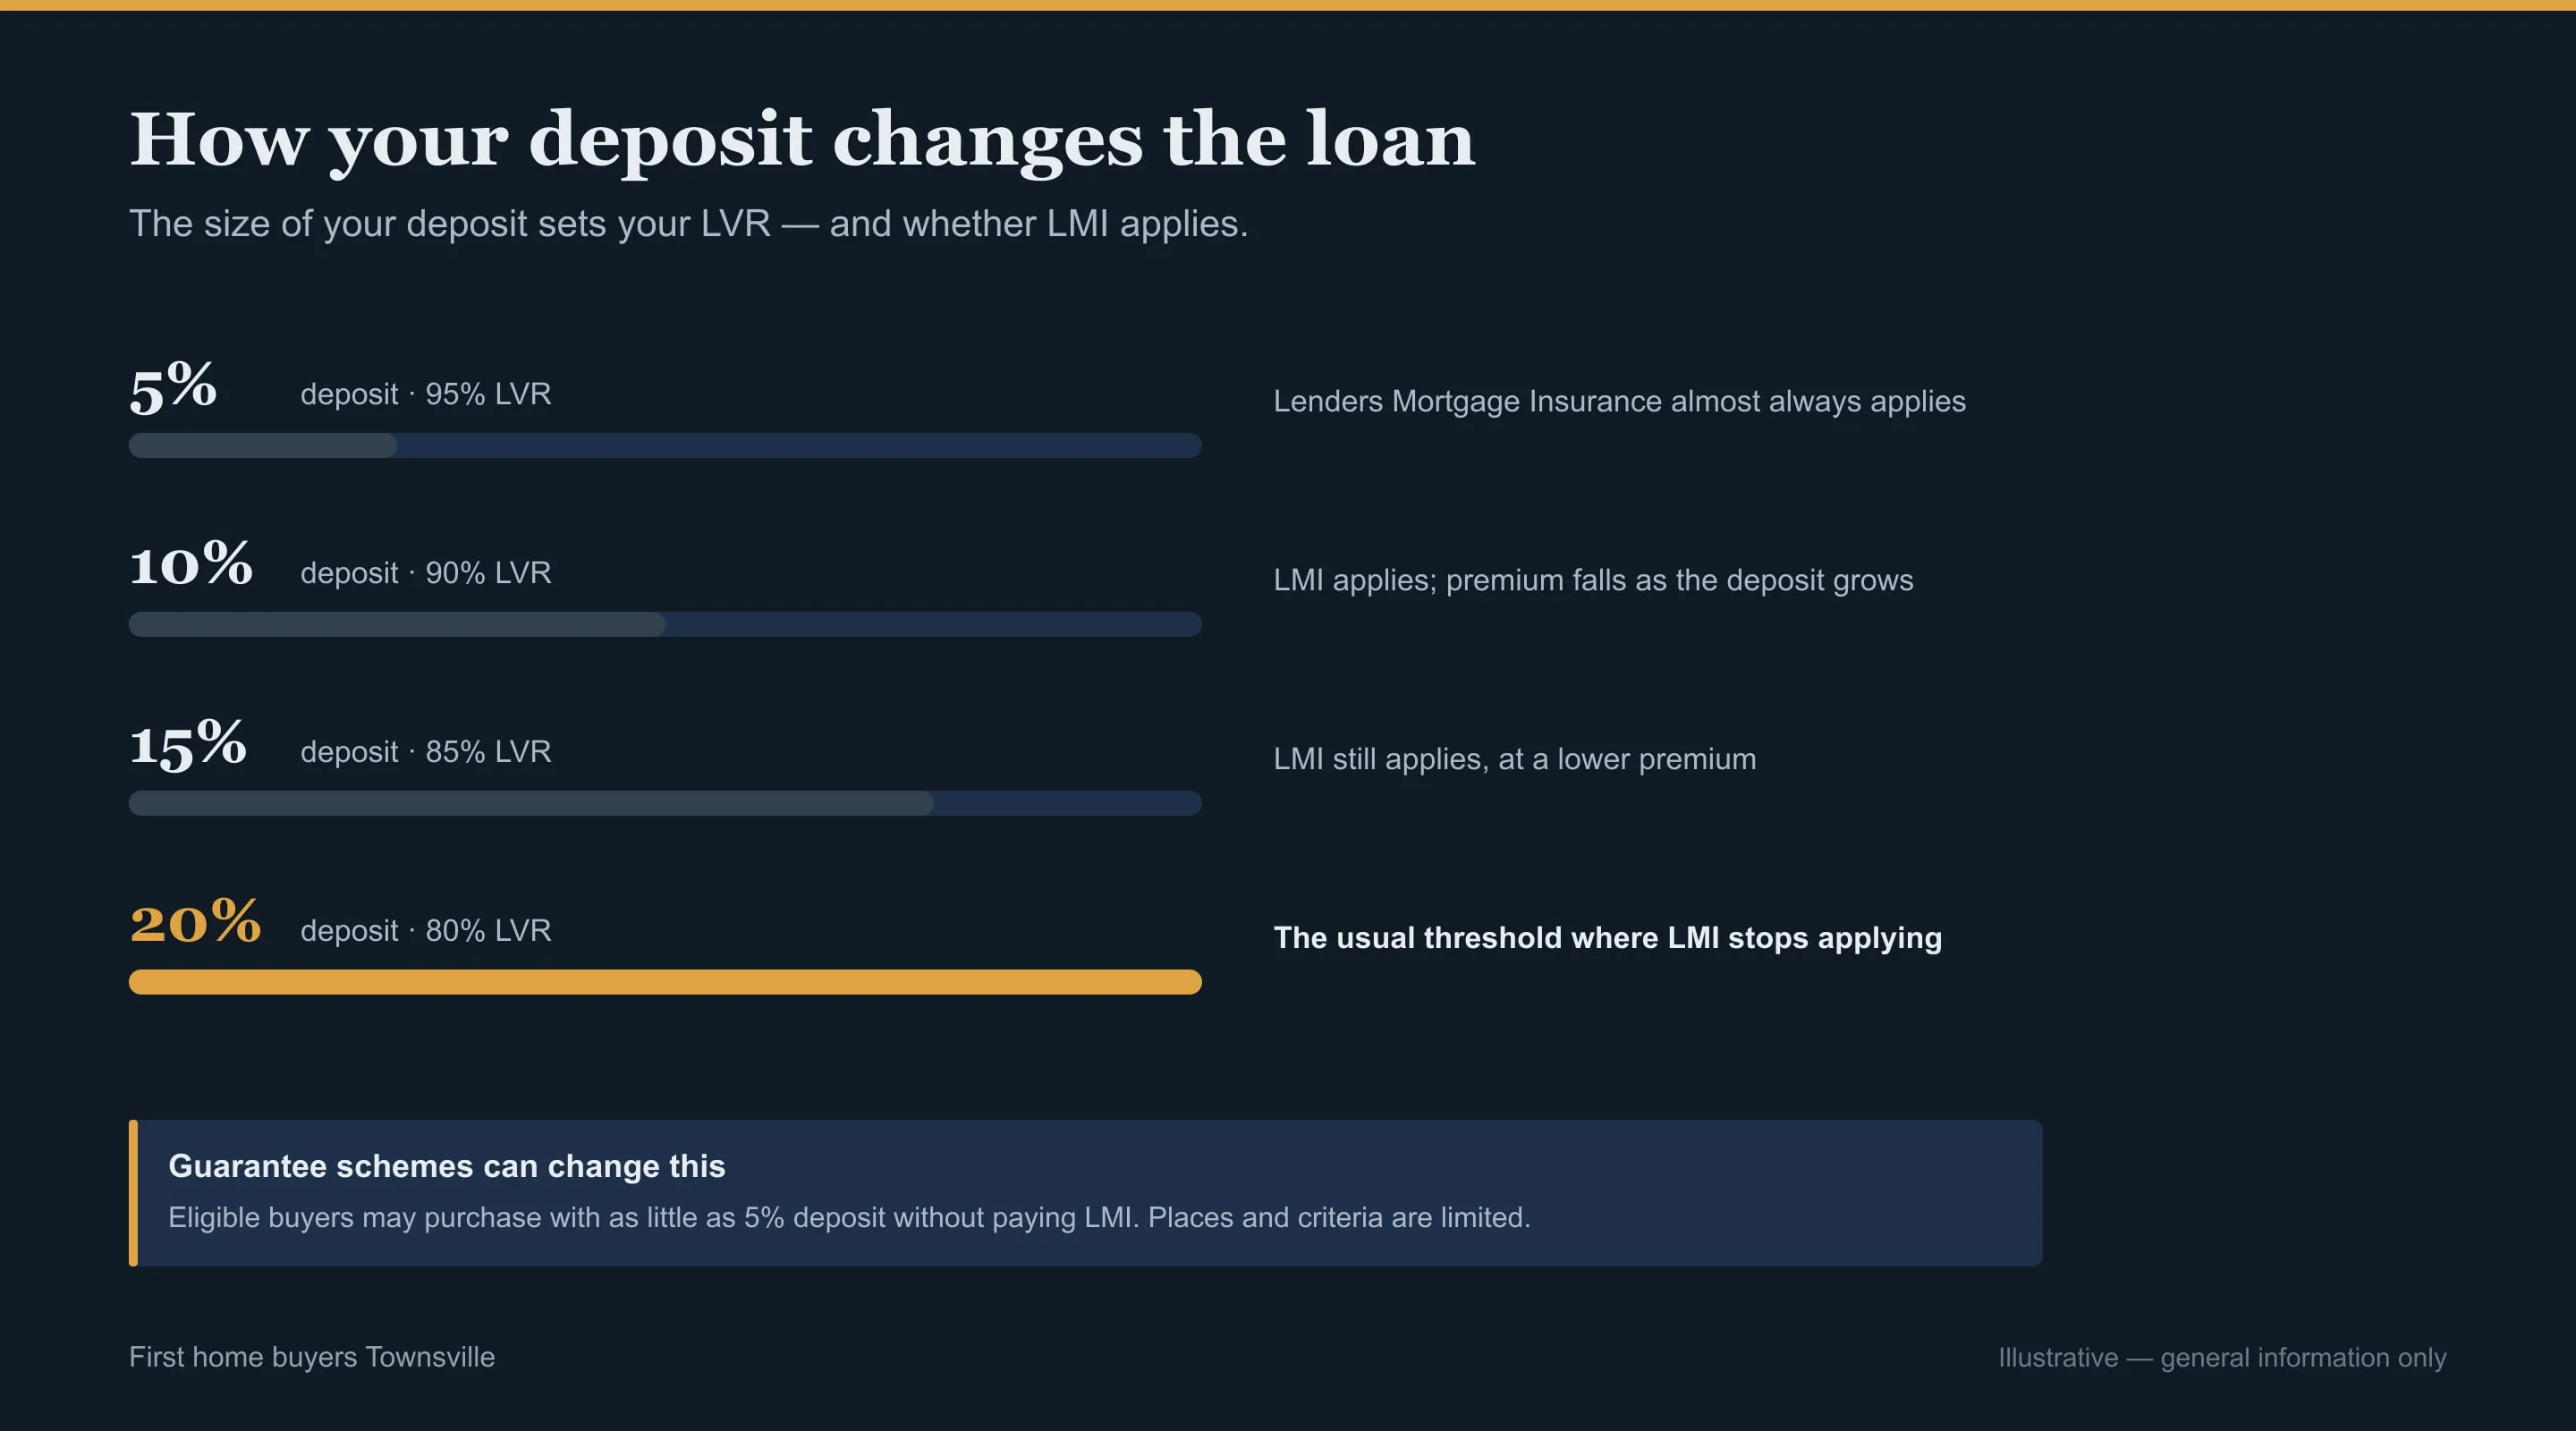
The schemes are not alternatives. A first home buyer building a new home in Townsville can hold the grant, pay no transfer duty, and use the First Home Guarantee to buy with a five per cent deposit and no Lenders Mortgage Insurance, all on the same purchase.
That combination changes what you need saved by a substantial margin, and it is the reason building is worth genuinely considering here rather than dismissing as slower. It is also the case that gets assembled wrongly most often, because each scheme is administered by a different body with its own forms and its own timing.
We map the whole stack against your purchase before you sign anything, then coordinate the lender, the solicitor and the applications so the pieces line up at settlement instead of one arriving late and unwinding the rest.
The Conditions You Have To Meet After Settlement
These are entitlements with obligations attached, and they can be clawed back. For the First Home Owner Grant you must move in within twelve months of settlement or completion and live there as your principal place of residence for a continuous six months. The duty concession carries its own occupancy requirement on a similar basis.
The practical consequence for you is that you cannot claim a first home benefit on a property you intend to rent out from day one. If your plan is to buy an investment first and live somewhere else, most of this page does not apply to you and we will say so rather than lodging something that gets reversed.
Where your circumstances might change inside those windows, whether that is a posting, a job move or a relationship change, tell us up front. It is far easier to plan around than to unwind afterwards.
What The Schemes Buy You In Townsville
The grant caps at $750,000 including land and build, and the First Home Guarantee caps the property price at $700,000 in Townsville, which is the "other areas" cap rather than the $1,000,000 figure that applies only to the Gold Coast and Sunshine Coast. Both caps still leave the majority of local stock in range, which is not true in most southern markets.
Where it gets tight is house-and-land in the newer estates, where the combined figure can approach the grant cap once inclusions are added. We check the total against the cap before you sign a build contract, because a modest run of upgrades can push you over the line and cost you the grant entirely.
Grants, Duty And Eligibility Questions
What happens if I turn out not to be eligible?
We tell you straight away and look at what does work. Not qualifying for the grant does not mean you cannot buy, because the duty concession or the First Home Guarantee may still apply, and plenty of first home buyers here proceed without the grant at all.
Can I get the grant on an established house in Townsville?
No. The First Home Owner Grant is limited to new homes that have not been lived in, or homes you build. Established purchases can still access the first home duty concession and the First Home Guarantee, which are separate schemes with different rules.
Can I claim the grant and then rent the property out?
Not immediately. You must move in within twelve months and live there for a continuous six months as your principal place of residence. Renting it out before you meet that condition can mean repaying the grant.
About us
Who Lines the Schemes Up
The person who answers keeps track of which body wants what and when, because the schemes are administered separately and none of them coordinate with each other. That coordination is the work rather than the eligibility check.
It is also the point at which someone has to say plainly that a scheme does not apply to you, which is a shorter answer than most people want and a better one than a lodged application that gets reversed.
-
Call
Monday to Friday, 9am to 5pm
-
Use the form
Better if you are on shift or on site and cannot talk
-
Email
info@mortgagebrokertownsville.net.au
Useful if you already have documents to hand over
-
Where we are
Townsville, QLD 4810
The city, the northern beaches and the districts inland
Find Out What You Qualify For in Townsville
If you are not sure which of the schemes you qualify for, that is the question worth settling before you start inspecting rather than after an offer.
Call (07) 4463 8031 Use The Form
Prefer to start from the beginning? Our Mortgage Broker Townsville page covers what we do and how we are paid.