
Specialist
Self-Employed Home Loans Townsville
Your tax return is written to minimise your taxable income, and a lender reading it literally sees a much smaller business than you run. That is why so many self-employed borrowers are told they cannot afford a loan they can plainly afford, and it is a presentation problem rather than an income one.
We arrange self-employed home loans Townsville wide for sole traders, contractors, tradespeople and company directors. We rebuild your income with the add-backs a lender will accept, then place the file with one that reads your structure properly.
Get Your Income Assessed in Townsville
How your business is structured, roughly what it earns, and whether your returns are lodged.
How We Present Your Income
We rebuild your assessable income line by line, apply the add-backs your shortlisted lender allows, and put the resulting figure in front of them with the working attached. Then we hold the file together through assessment, because self-employed applications attract more questions and those get answered here rather than forwarded back to you.
It costs you nothing to find out where you stand. The lender pays us on settlement, so the assessment is free, and that includes the case where the honest answer is to lodge a return first and apply in three months.
Getting Your Income Assessed Properly
Most declined self-employed applications fail on presentation rather than on income. This is the order that avoids that.
-
We work out what your income really is
Not the taxable figure at the bottom of the return. We rebuild it with the add-backs a lender will accept, and the number is usually higher than you expect.
Day one
-
We match you to a lender that reads your structure
Sole trader, trust, company, or a mix. Lenders differ enormously in how they handle each, and picking the wrong one is what produces most declines.
-
We build the file before we lodge it
Returns, notices of assessment, BAS, an accountant’s letter where it helps. Have your accountant’s contact details ready, because a single clarifying letter often resolves what would otherwise be a decline.
Before submission
-
We lodge and hold it together
Self-employed files attract more questions from assessors. We answer them rather than passing each one back to you.
Through to settlement
Before You Get In Touch
What documents do you need from me to start?
Two years of personal and business tax returns with the ATO notices of assessment, your recent BAS, and business bank statements. If you do not have all of that, start with what you have, because there are lenders that assess on bank statements and BAS instead.
How long does a self-employed application take?
Longer than a payslip application, because there is more for the assessor to verify and more that can prompt a question. Build extra time into a finance clause rather than assuming a standard timeframe, particularly if your returns are recent or the two years look different.
Do you charge self-employed clients a fee?
No. We are paid by the lender when the loan settles, regardless of how much work the file takes. There is no charge for the assessment and no charge if you decide not to proceed.
What Lenders Add Back To Your Income
An add-back is a deduction the lender restores to your income because no cash actually left the business. It is how the gap between your taxable figure and what you genuinely earn gets closed, and it is the difference between a decline and an approval on identical trading.
Depreciation is a paper deduction with no cash leaving the business, so most lenders add it straight back. So do additional superannuation contributions above the compulsory rate, one-off expenses that will not recur, interest on debts being paid out by the refinance, and in some cases a portion of a company profit retained rather than drawn.
Which of these a particular lender accepts varies, and that variance is worth real borrowing capacity. We rebuild your income line by line, apply the add-backs the shortlisted lender allows, and put the resulting figure in front of them with the working attached. That is a presentation task, not an accounting one. We are not touching your tax position, only how the existing numbers are read.
What You Need If You Have Been Trading Two Years
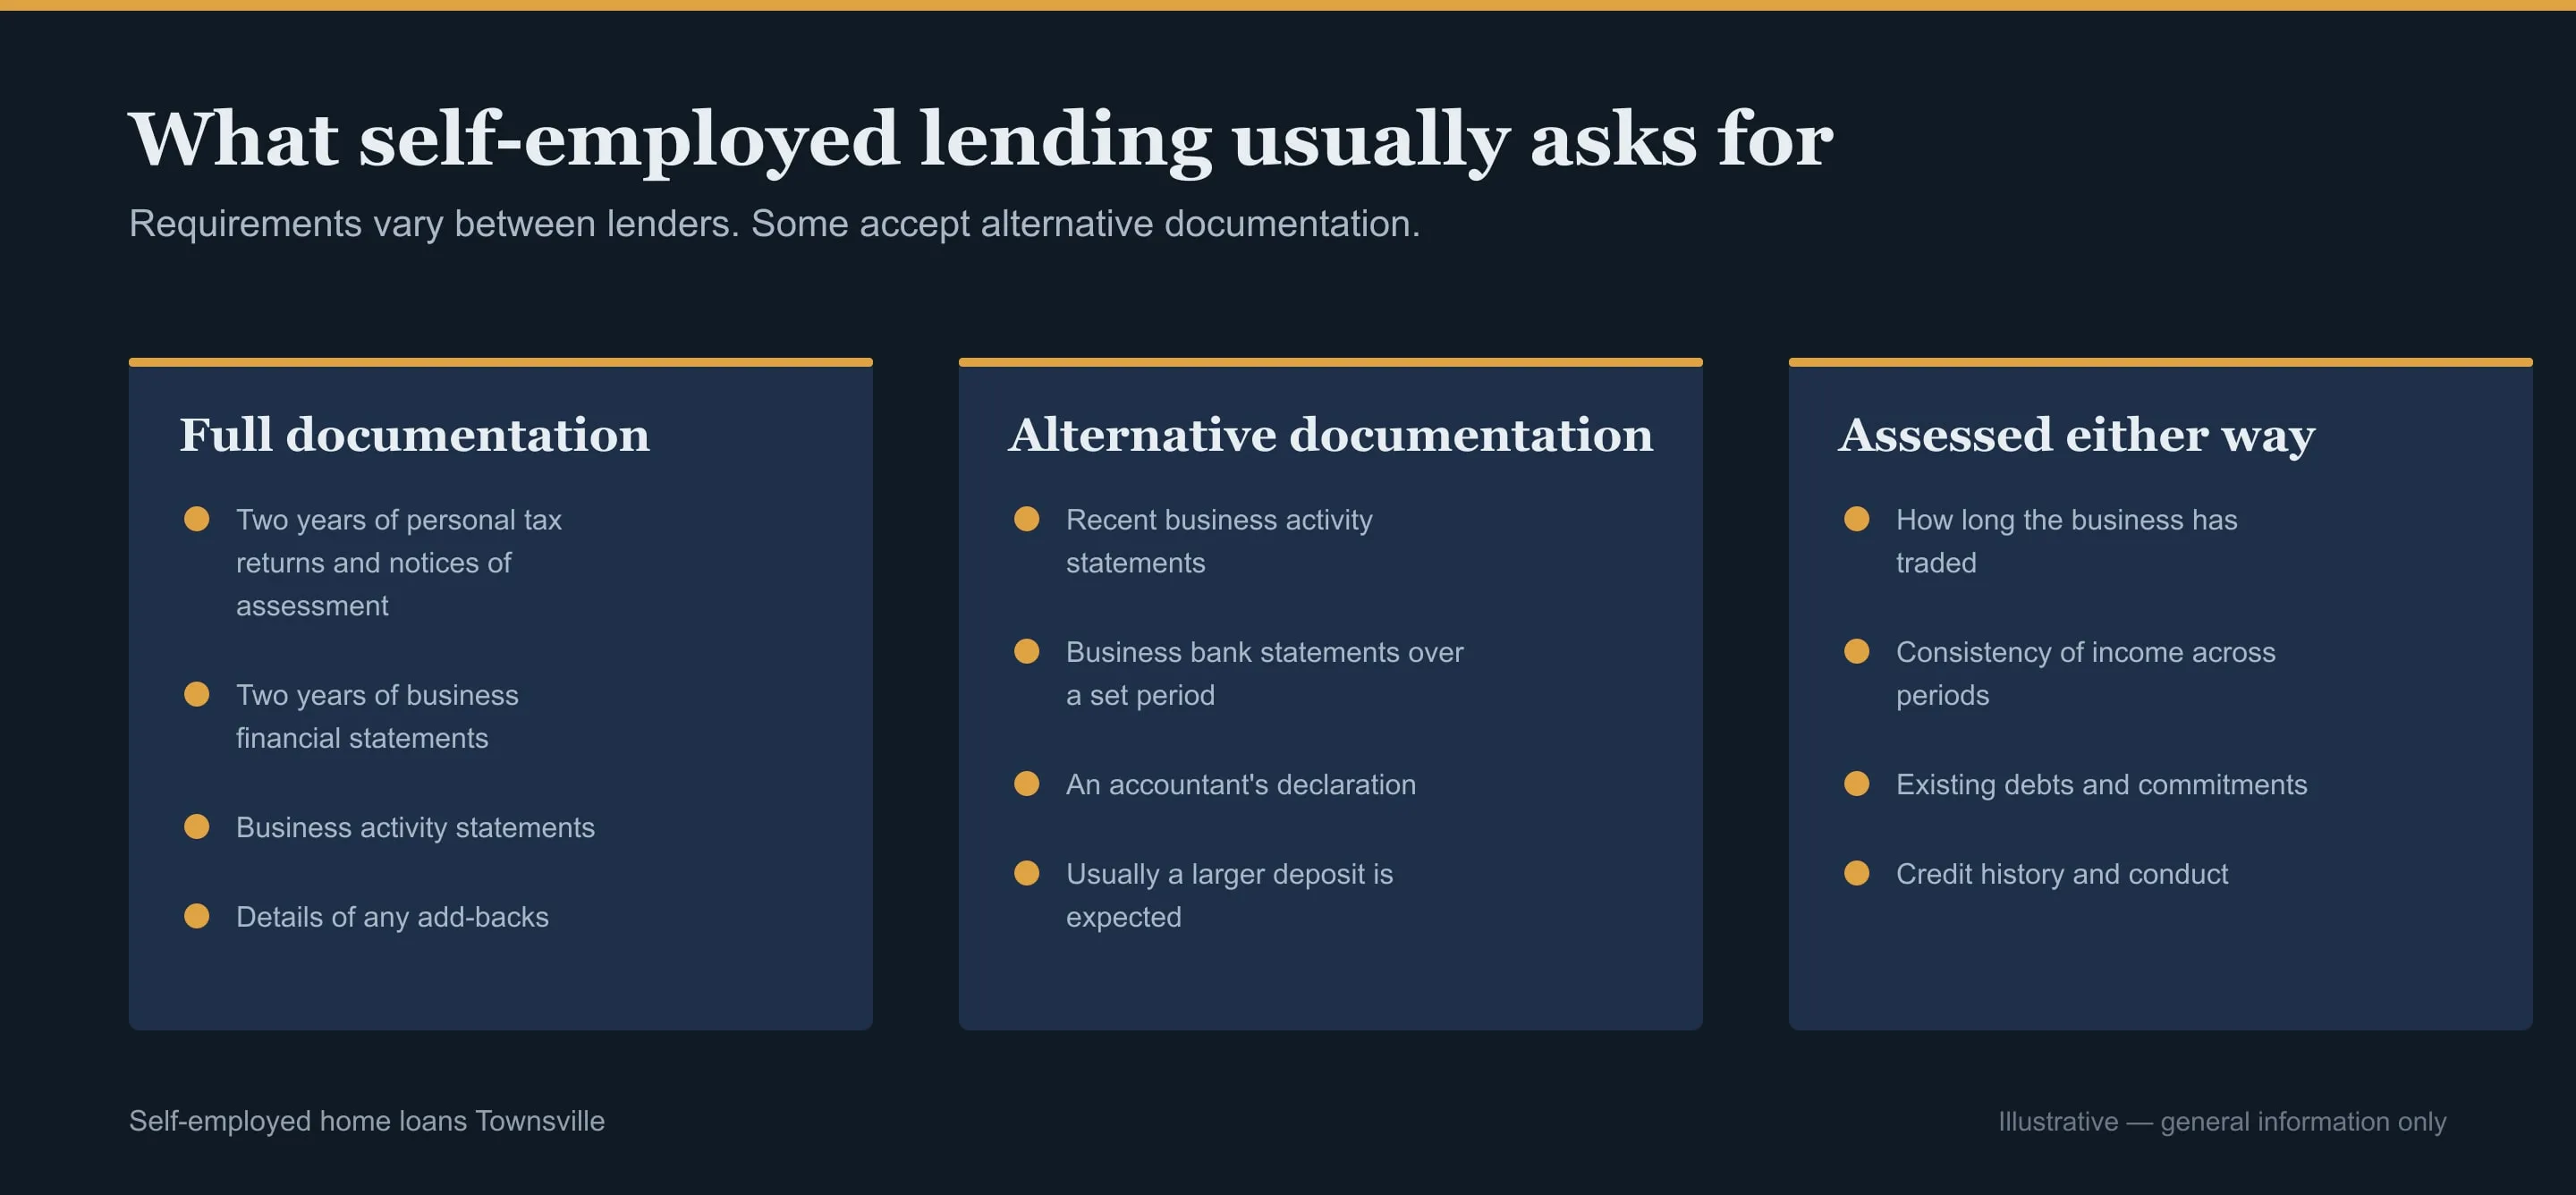
The standard full-doc path wants two years of personal and business tax returns with matching ATO notices of assessment, recent BAS, and business bank statements. Where the two years show very different figures, most lenders use the lower one, so a strong recent year does not automatically carry a weak earlier one.
That last point is worth planning around. If your most recent year is materially better, some lenders will consider it on its own with an accountant’s confirmation that the improvement is sustained. Others will not under any circumstances. Knowing which is which before you apply is the difference between an approval and a decline you then have to explain to the next lender.
Borrowing Without Two Years Of Returns
If you have been trading under two years, or your returns are not yet lodged, there is still a path. Alt-doc lending substitutes other evidence for tax returns, typically six to twelve months of business bank statements, your BAS, and a signed declaration of income supported by your accountant.
It is a legitimate, regulated product rather than a loophole. The lender still has to verify your income under responsible lending obligations; it just accepts a different form of proof. The trade-offs are real: alt-doc loans generally price higher than full-doc, and most lenders cap the loan-to-value ratio lower, so you will usually need a larger deposit.
We will tell you honestly whether waiting a few months to lodge a return and going full-doc leaves you better off than borrowing now on alt-doc terms. Often it does. Where you need to move on a property before then, we structure the alt-doc application and plan the refinance to full-doc pricing once your returns are in.
ATO Debt And Business Arrears
An outstanding ATO liability will surface. It shows up in your BAS, your statements and your accountant’s letter, and undisclosed debt discovered mid-assessment does more damage than the debt itself.
It is not automatically fatal. A debt on a formal payment arrangement that you are meeting is treated very differently from one in default, and some lenders will proceed where others will not look at it at all. Tax debt reported to credit reporting bureaus is the harder case, and there the sequence usually has to be clearing or formalising the arrangement before an application is worth lodging.
Tell us up front. We would rather structure around it, or tell you to wait three months and fix it first, than have an assessor find it and decline the file.
Alt-doc pricing and LVR caps vary by lender and are not listed. We confirm both against your situation before you rely on either.
Contractors And Business Owners Across Townsville
A large share of the Townsville workforce is in mining services, construction, transport and trades, and a lot of that is contracted rather than salaried. If you invoice through your own ABN, work a FIFO roster out of Townsville, or run a business supplying the resource sector, you are in the group lenders handle least consistently.
The specific problems we see across Townsville are income that arrives in irregular lumps rather than fortnightly, a single dominant client that some lenders treat as employment risk, and roster income that looks volatile across a twelve-month view. Each of those has lenders that handle it sensibly and lenders that do not. We place you with the former rather than letting a policy mismatch decide your outcome.
Income, Documents And ATO Questions
I have been trading under two years, is it worth applying?
Often yes. Alt-doc lending uses business bank statements, BAS and an accountant’s declaration instead of tax returns. It usually needs a larger deposit and prices higher than full-doc, so we will tell you whether waiting to lodge a return leaves you better off.
Will my tax deductions count against me?
Some of them get added back. Depreciation, extra superannuation, one-off expenses and interest being refinanced are commonly restored to your assessed income because no cash actually left the business. Which ones a lender accepts varies, and it can change your capacity substantially.
Can I get a loan with an ATO debt?
Sometimes. A debt on a payment arrangement you are meeting is treated very differently from one in default or reported to a credit bureau. Tell us early so we can either structure around it or advise you to resolve it first, rather than having an assessor find it.
About us
Who Rebuilds Your Figures
The person who answers rebuilds your income the way a lender reads it, applies the add-backs the shortlisted lender allows, and puts the working in front of them. A file that is well presented is assessed differently from one that is merely complete.
It is slower work than a payslip file and it attracts more questions from assessors. Those get answered here rather than forwarded back to you with a request for more documents.
-
Call
Monday to Friday, 9am to 5pm
-
Use the form
Better if you are on shift or on site and cannot talk
-
Email
info@mortgagebrokertownsville.net.au
Useful if you already have documents to hand over
-
Where we are
Townsville, QLD 4810
The city, the northern beaches and the districts inland
Get Your Income Assessed in Townsville
If your returns are not lodged, or the last two years look nothing alike, that is the ordinary case here rather than a problem to apologise for.
Call (07) 4463 8031 Use The Form
Prefer to start from the beginning? Our Mortgage Broker Townsville page covers what we do and how we are paid.